GAME: From Specialist Retailer to Gaming Commerce Empire? research poster
All Research
09Platform Value 12 min readAugust 2026
Coverage · United Kingdom · EuropeSector · Gaming & Specialist RetailFormat · Six-page audit

GAMEFrom Specialist Retailer … To Gaming Commerce Empire?

Once the UK's leading gaming retailer. Now a fragmented, underleveraged brand inside a $200BN+ global gaming economy. This isn't decline — it's untapped platform value.

Annual Revenue

£600M+

Store Footprint

200+

Loyal Customers

3M+

Upside Potential

£3BN+

The Thesis

The market is pricing GAME as a retailer when it is actually a gaming ecosystem play. Deep customer trust, a physical plus digital network, trade-in data and access to next-gen gaming audiences are platform assets — they are simply not being owned as a stack.

Exhibit · Report Cover

09 · Platform Value

GAME: From Specialist Retailer to Gaming Commerce Empire? report cover
GAME: From Specialist Retailer to Gaming Commerce Empire?August 2026 · United Kingdom · Europe
01

The mispricing

GAME is valued as a declining high street retailer, a low-margin trade-in business, a price-taker competing with Amazon and a physical store liability.

In reality it holds the deepest gaming customer trust in the UK, a pre-owned inventory network no pure-play can replicate, and a high-intent, high-frequency category that most retailers would pay heavily to enter.

The market is pricing a retailer when it's actually a gaming ecosystem play.
  • 3M+ active customers with a multi-decade brand connection — undervalued community
  • Trade-in and pre-owned are high margin with a sustainability tailwind — under-monetised
  • Stores are experience hubs: launch events, community, fulfilment points
  • No owned IP or content play — value currently captured by Sony, Microsoft, Steam and Epic
02

The 5x growth engine

The reposition is from retailer to platform owner. First, own the gaming loyalty stack: unified points across stores and digital, tiers, early access, exclusive drops and data-driven personalisation. Loyalty becomes lifetime value.

Second, scale a re-commerce powerhouse — a refurbished and pre-owned certified marketplace with AI pricing, warranty and grading. High margin, sustainable, defensible.

Third, a digital-first ecosystem: best-in-class app, subscriptions, digital wallet with instant credit and one-click everything. Then a content and community hub — launch events, creator collabs, studios, UGC and tournaments. Finally private label: GAME-branded accessories, merch and hardware for own brand, own margin.
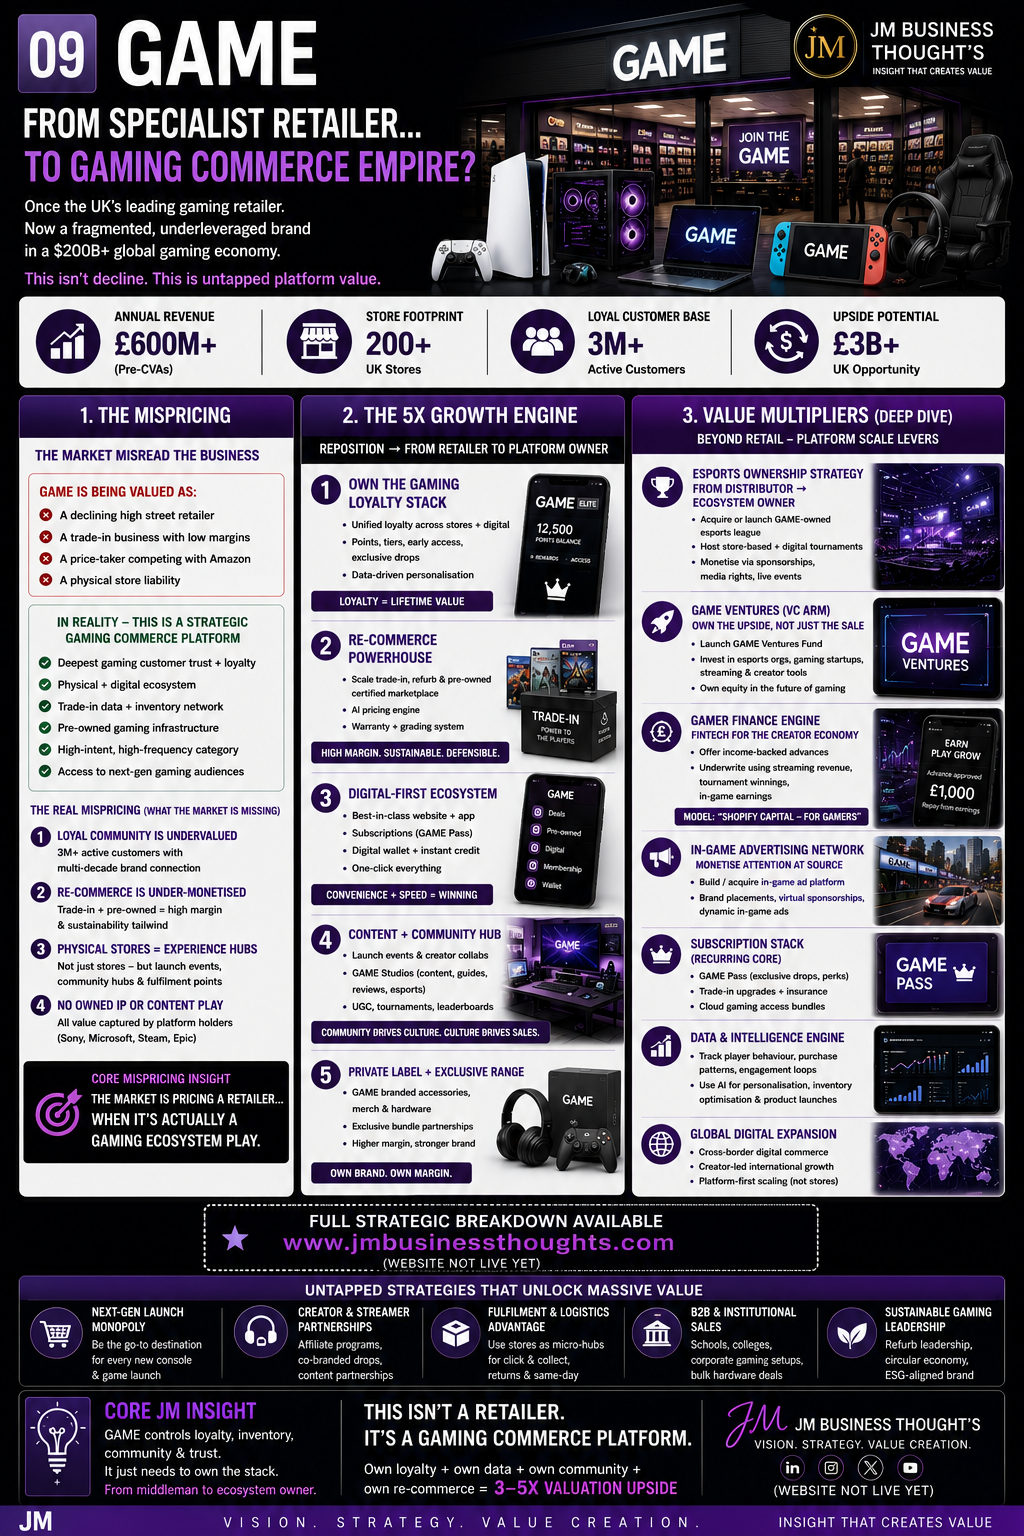
Own loyalty + own data + own community + own re-commerce.
03

Value multipliers beyond retail

Each lever below carries its own economics and can be valued independently of the core store estate.

  • Esports ownership: from distributor to ecosystem owner — leagues, in-store tournaments, sponsorship and media rights
  • GAME Ventures (VC arm): invest in esports orgs, gaming startups and creator tools to own the upside, not just the sale
  • Gamer finance engine: income-backed advances underwritten on streaming, tournament and in-game earnings
  • In-game advertising network: brand placements, virtual sponsorships and dynamic in-game ads
  • Subscription stack: GAME Pass with exclusive drops, trade-in upgrades, insurance and cloud gaming bundles
  • Data and intelligence engine: player behaviour and engagement loops driving personalisation and inventory optimisation
  • Global digital expansion: cross-border commerce and creator-led international growth, platform-first not store-first
04

Untapped strategies

Next-gen launch monopoly — become the destination for every new console and game launch. Creator and streamer partnerships through affiliate programs, co-branded drops and content deals.

Fulfilment advantage: stores as micro-hubs for click and collect, returns and same-day. B2B and institutional sales into schools, colleges and corporate gaming setups. Sustainable gaming leadership through refurb and circular economy positioning.

05

The risk case

Platform ambitions fail when the store estate stays a cost line instead of becoming fulfilment and experience infrastructure. Trade-in economics also depend on hardware cycles that GAME does not control.

Owning the stack requires data, product and community capability that a retail organisation has never had to build.

The Multiplier Framework

8 compounding levers

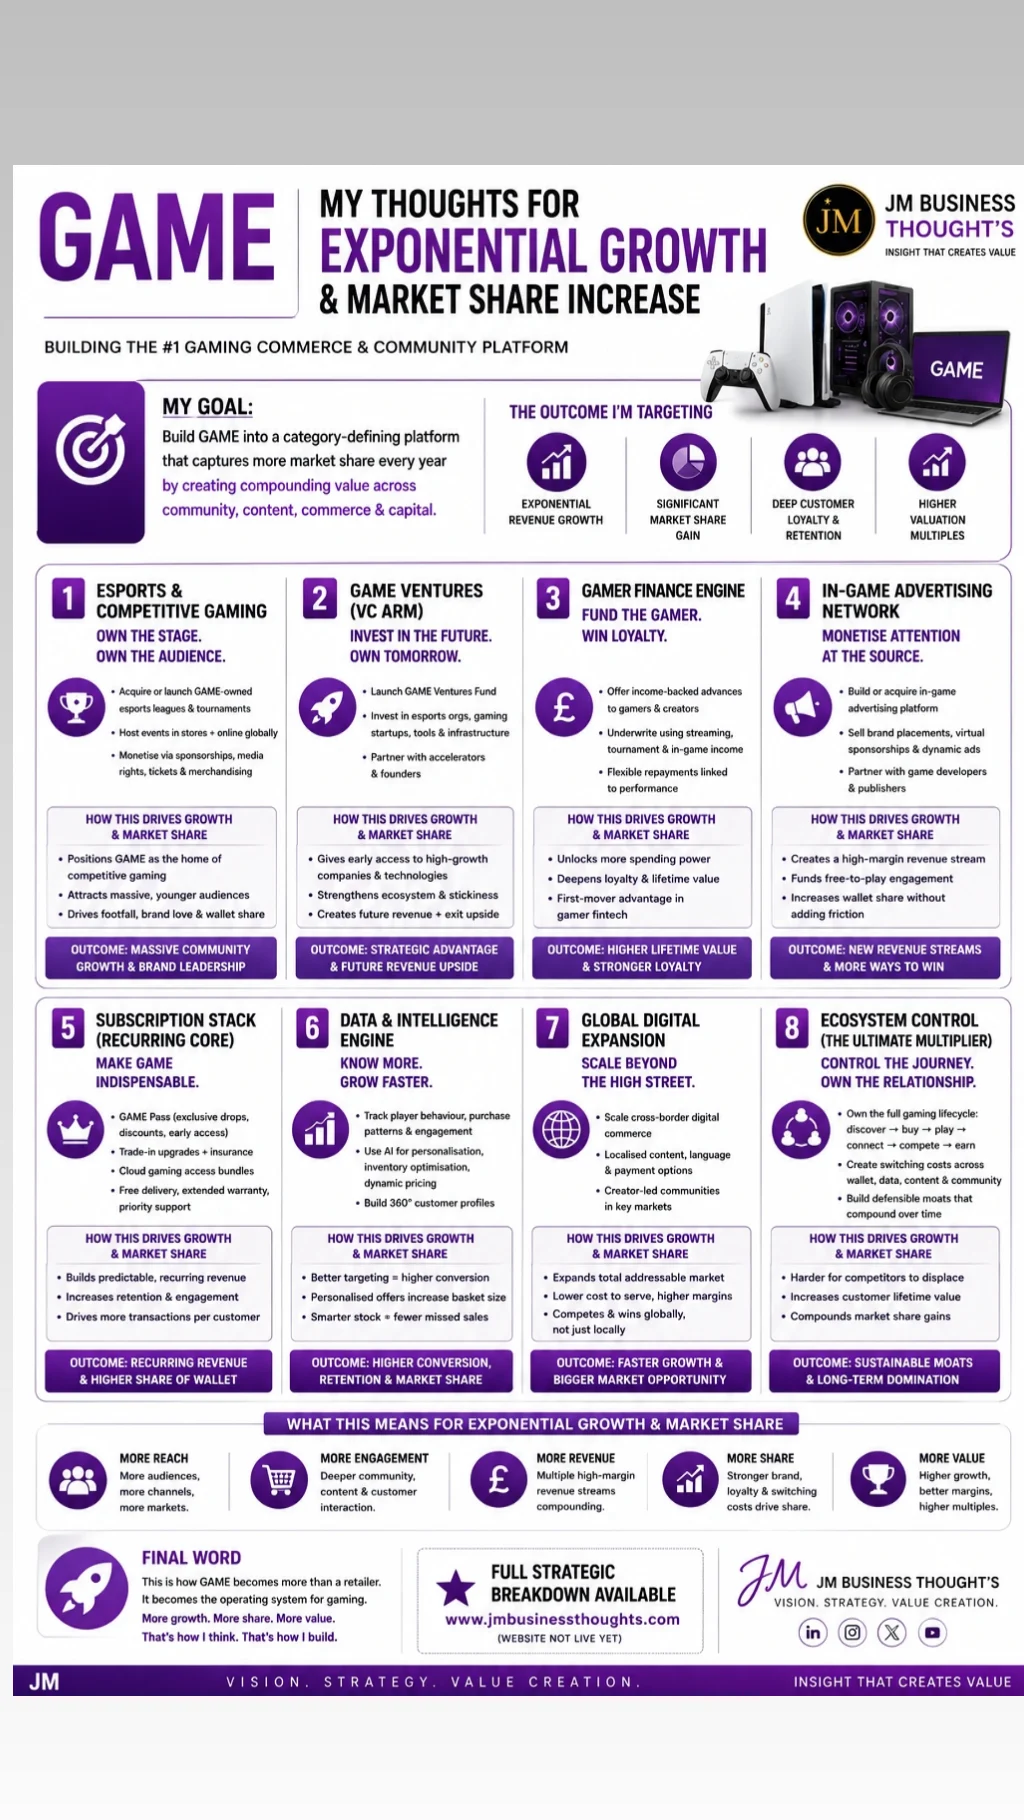
Eight compounding levers turn GAME from a specialist retailer into the operating system for gaming — community, content, commerce and capital in one stack. Each lever is separately fundable and separately valuable.

01

Esports & Competitive Gaming

Own the stage. Own the audience.

  • Acquire or launch GAME-owned esports leagues and tournaments
  • Host events in stores and online globally
  • Monetise via sponsorship, media rights, ticketing and merchandise

Outcome · Massive community growth and brand leadership

02

GAME Ventures (VC Arm)

Invest in the future. Own tomorrow.

  • Launch a GAME Ventures fund
  • Back esports orgs, gaming startups, tools and infrastructure
  • Partner with accelerators and founders for deal flow

Outcome · Strategic advantage and future revenue upside

03

Gamer Finance Engine

Fund the gamer. Win the loyalty.

  • Income-backed advances to gamers and creators
  • Underwrite on streaming, tournament and in-game income
  • Flexible repayments linked to performance

Outcome · Higher lifetime value and stronger loyalty

04

In-Game Advertising Network

Monetise attention at the source.

  • Build or acquire an in-game advertising platform
  • Sell brand placements, virtual sponsorships and dynamic ads
  • Partner with developers and publishers for inventory

Outcome · High-margin revenue that funds free-to-play engagement

05

Subscription Stack

Make GAME indispensable.

  • GAME Pass: exclusive drops, discounts and early access
  • Trade-in upgrades plus insurance and extended warranty
  • Cloud gaming bundles, free delivery and priority support

Outcome · Recurring revenue and a higher share of wallet

06

Data & Intelligence Engine

Know more. Grow faster.

  • Track player behaviour, purchase patterns and engagement
  • AI for personalisation, inventory optimisation and dynamic pricing
  • Build 360° customer profiles across store and digital

Outcome · Higher conversion, retention and market share

07

Global Digital Expansion

Scale beyond the high street.

  • Scale cross-border digital commerce
  • Localised content, language and payment options
  • Creator-led communities in key markets

Outcome · Faster growth against a bigger addressable market

08

Ecosystem Control

Control the journey. Own the relationship.

  • Own the full lifecycle: discover → buy → play → connect → compete → earn
  • Create switching costs across wallet, data, content and community
  • Build defensible moats that compound over time

Outcome · Sustainable moats and long-term category domination

GAME: From Specialist Retailer to Gaming Commerce Empire? full strategic breakdown
The full strategic breakdown: eight compounding levers across community, content, commerce and capital.

The Verdict

This isn't a retailer. It's a gaming commerce platform waiting to own its stack — from middleman to ecosystem owner, a 3–5x valuation upside.

JM founder signature
68 · PureGym — Fitness At Scale. More Personal. More Inclusive.67 · SIXT — Smarter Mobility. Greater Availability. A More Connected Tomorrow.66 · Sendwave — Money That Moves With Intelligence.65 · McDonald’s — Serving The Future With AI.64 · Compare the Market — Smarter Comparison. Better Matches. Brighter Tomorrows.63 · WeBuyAnyCar — Smarter Pricing. Faster Offers. Better Conversion.62 · Primark — Affordable Fashion. Greater Possibilities With AI.61 · Starbucks — Smarter Stores. Stronger Loyalty. Better Margins.60 · IKEA — AI-Powered Home Retail at Global Scale59 · H&M — Smarter Fashion. Brighter Tomorrow.58 · WeWork — The Value Wasn't Lost. It Was Mispriced.57 · Yahoo — The Value Wasn't Lost. It Was Mispriced.56 · Nando's UK — Smarter Restaurants. Stronger Loyalty. Better Margins.55 · The Amplifier54 · The Body Shop53 · Arcadia Group52 · Cazoo51 · Blockbuster50 · Carpetright49 · Wilko48 · Mothercare47 · Phones 4u46 · Farfetch45 · Jumia44 · Toys ‘R’ Us43 · The Collateral Gap — Part One41 · The Amplifier40 · Africa Bee Farming39 · Kenya Airways38 · Africa Greenhouse Farming37 · Uganda Tourism Board36 · Boots UK35 · Biffa (UK)34 · NatWest33 · Skip Hire Companies UK33 · The Audit32 · The Lean Company31 · Africa Mushroom Farming29 · The Rider Economy Nobody Verified28 · The Layer Underneath the Layer27 · Independent Timber Yards & Jewson Timber26 · Link Up TV & GRM Daily25 · East African Portland Cement42 · International Student Credential & Financial Verification — Part One24 · The Supply Chain Inside the Supply Chain23 · The White Space, Mapped22 · The Real Opportunity21 · Greencore20 · West Ham United19 · Roofings Group Uganda18 · Mombasa Port17 · Auto Trader UK16 · Uganda Coffee Development Authority15 · Brookside Dairy14 · GraceKennedy13 · Rightmove12 · Manchester United11 · Greggs30 · Twiga Foods10 · Uchumi09 · Konga08 · Edcon06 · Claire's05 · Boohoo04 · Argos