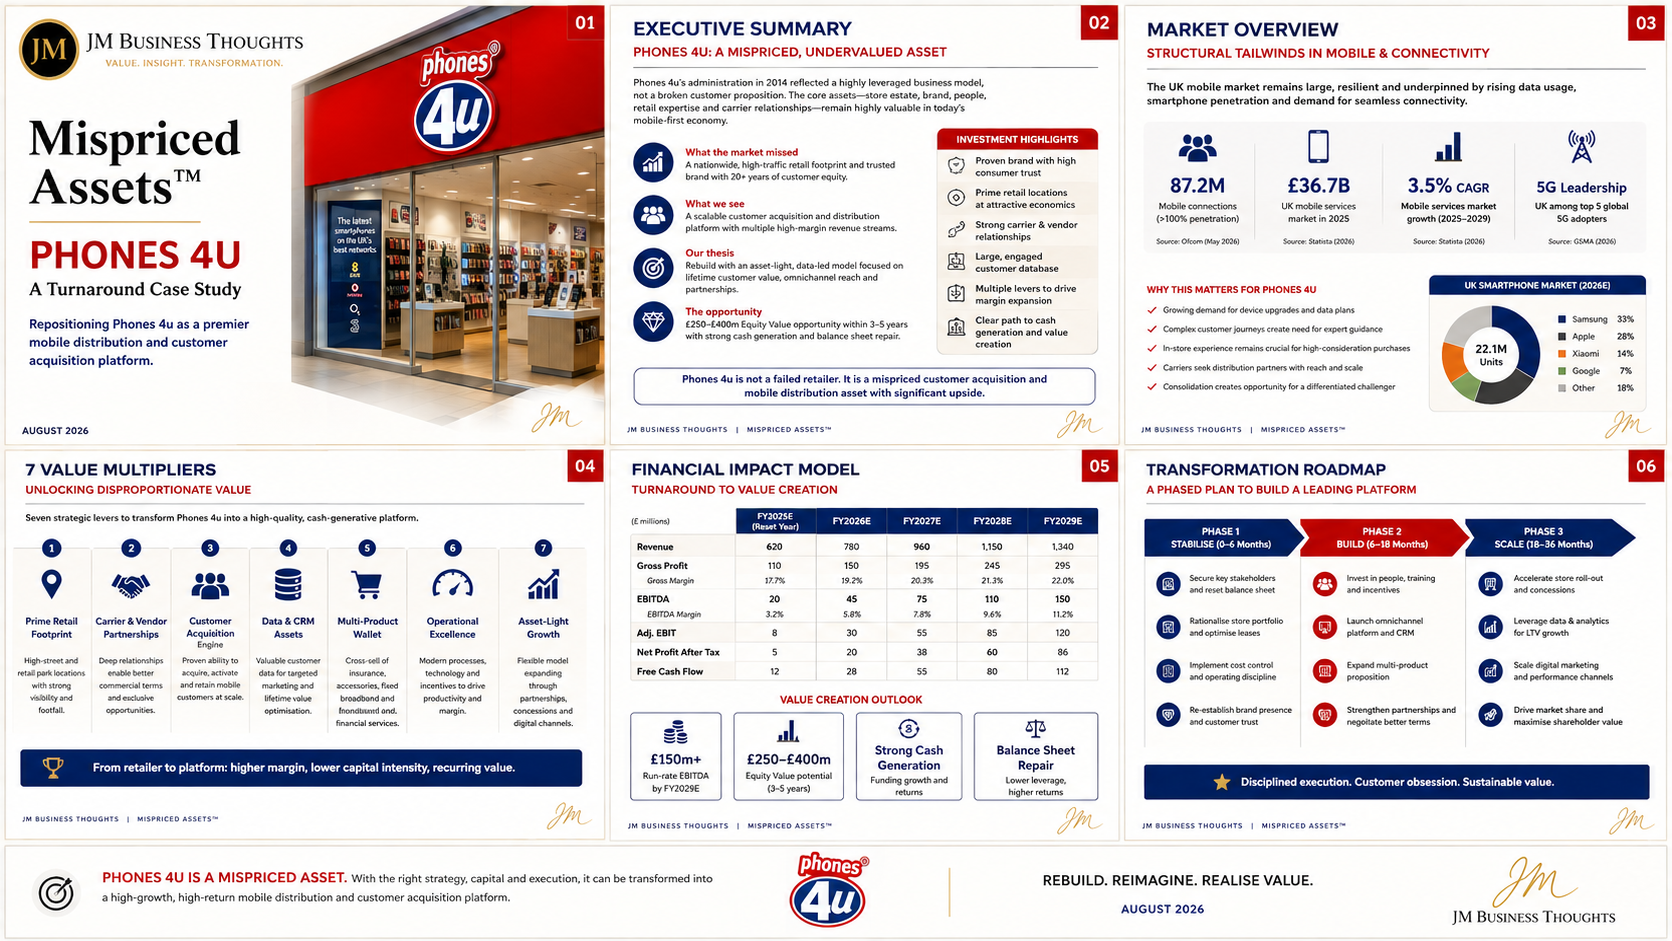
Phones 4u is not a failed retailer. It is a mispriced customer acquisition and mobile distribution asset with significant upside — and that distinction is the entire investment case.
What the market missed: a nationwide, high-traffic retail footprint and a trusted brand carrying more than twenty years of customer equity. Those are acquisition channels, not shop leases, and they were cleared at liquidation speed rather than at channel value.
What we see: a scalable customer acquisition and distribution platform with multiple high-margin revenue streams — connections, upgrades, insurance, accessories, fixed broadband and financial services layered onto a single footfall base.
Our thesis: rebuild with an asset-light, data-led model focused on lifetime customer value, omnichannel reach and partnerships. The opportunity: £250M – £400M of equity value within three to five years, with strong cash generation and balance sheet repair.
Investment highlights are the same five every carrier-adjacent distributor wants and almost none can assemble at once: a proven brand with high consumer trust, prime retail locations at attractive economics, strong carrier and vendor relationships, a large and engaged customer database, multiple levers to drive margin expansion, and a clear path to cash generation and value creation.