International Student Credential & Financial Verification — Part One: The Scale & The Fraud research poster
All Research

The Infrastructure Layer Series™

Who owns the rails underneath the AI economy — and where nobody has built them yet.

42Infrastructure Layer™ 18 min readAugust 2026
Coverage · United Kingdom · India · Nigeria · Kenya · ChinaSector · Education Export · Identity & Document VerificationFormat · Six-page audit

International Student Credential & Financial Verification — Part OnePart One of Three

A £40 billion UK export industry with a 40%-forged-documents fraud rate, growing fastest in exactly the markets least equipped to absorb it. One fraud chain repeats identically across India, Nigeria, Kenya and China — because nothing in the admissions pipeline checks whether a document has already been caught somewhere else.

UK Education Export Target, 2030

£40BN

Forged Docs Share of Detected Fraud

40%

India — Largest Source Country

~95,000

Nigeria — Largest African Sender

37,155

Kenyan Visa Applications, H1 2026

+20%

Kenyan Growth, Full-Year 2025

+44%

Share of UK University Revenue

23%

UCL International Fees, 2023/24

£678M

The Thesis

International education is one of the United Kingdom's largest single export industries — not a compliance sideline. It runs on documents: bank statements, academic certificates, sponsorship letters, appointment confirmations. Every one of those documents is verified independently, university by university, with no shared record of what has already been rejected. The result is a fraud market with near-zero marginal cost of reuse: a forged UBA statement rejected in Lagos on Monday can be submitted, unchanged, to four other institutions by Friday. This is not a detection problem — individual admissions teams catch forgeries constantly. It is a memory problem. The infrastructure layer that would close it — check once, flag everywhere — does not exist, has an identifiable buyer with an existing budget line, and is unowned.

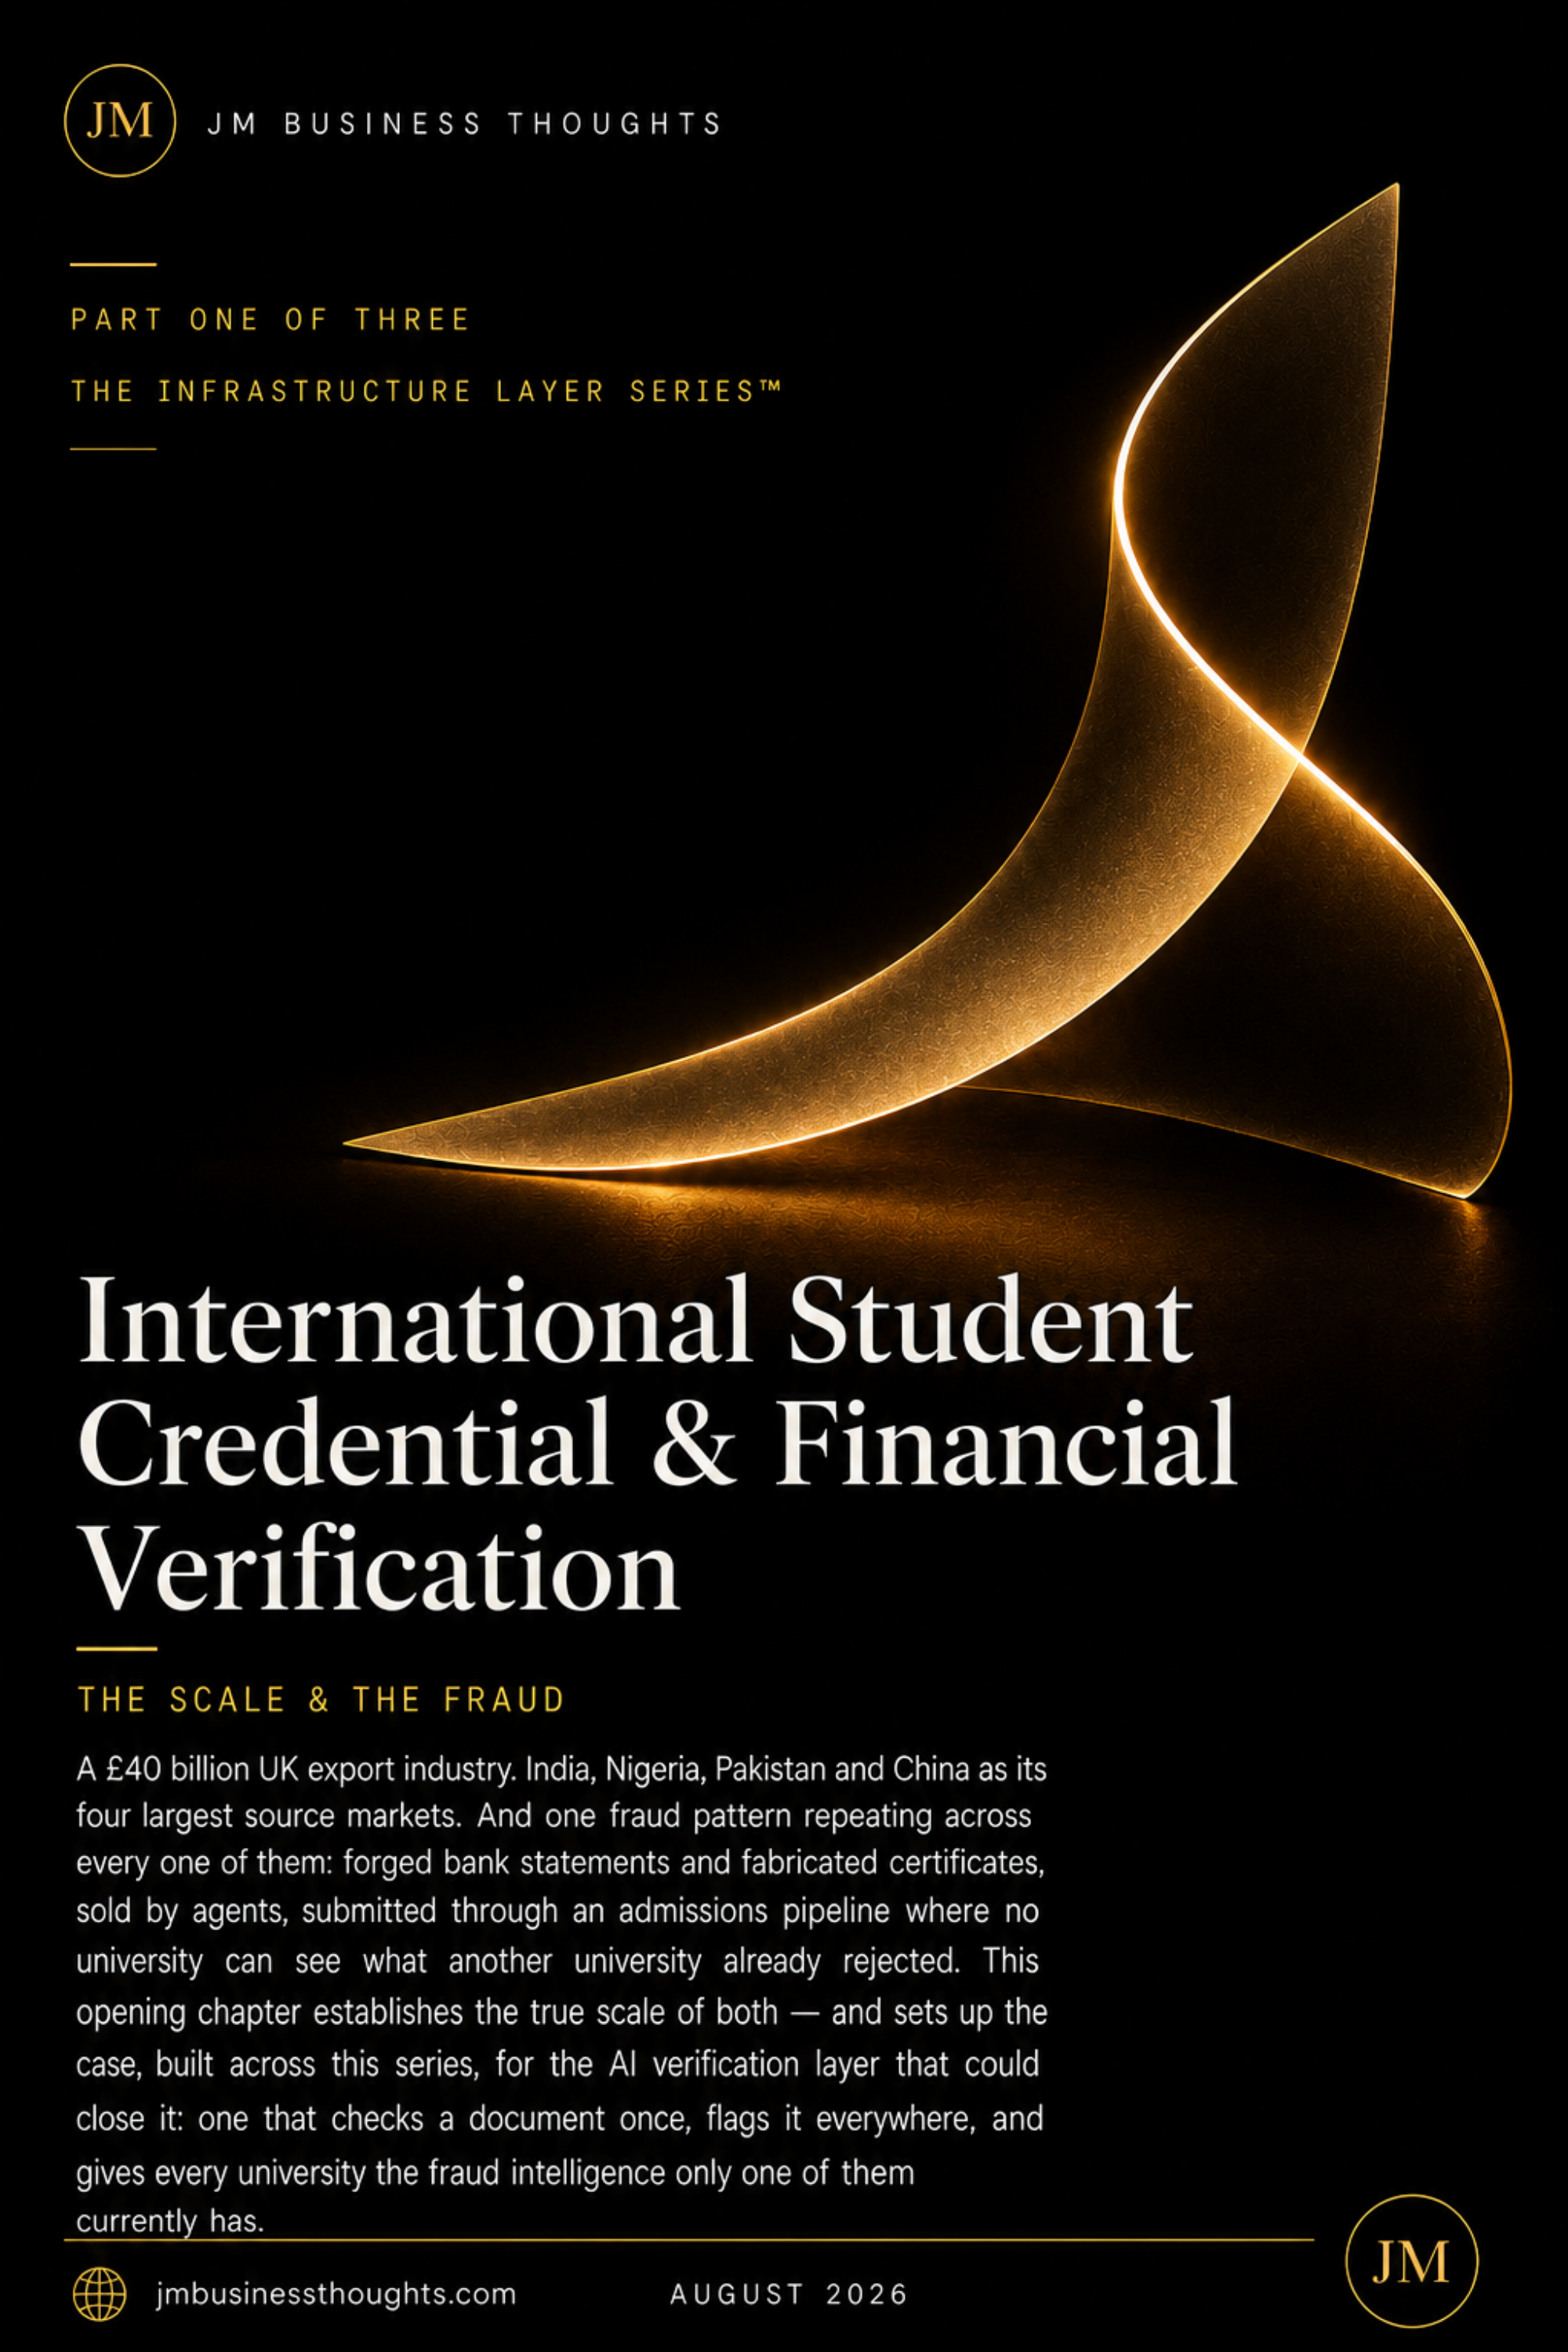
Exhibit · Report Cover

42 · Infrastructure Layer™

International Student Credential & Financial Verification — Part One: The Scale & The Fraud report cover
International Student Credential & Financial Verification — Part One: The Scale & The FraudAugust 2026 · United Kingdom · India · Nigeria · Kenya · China
01

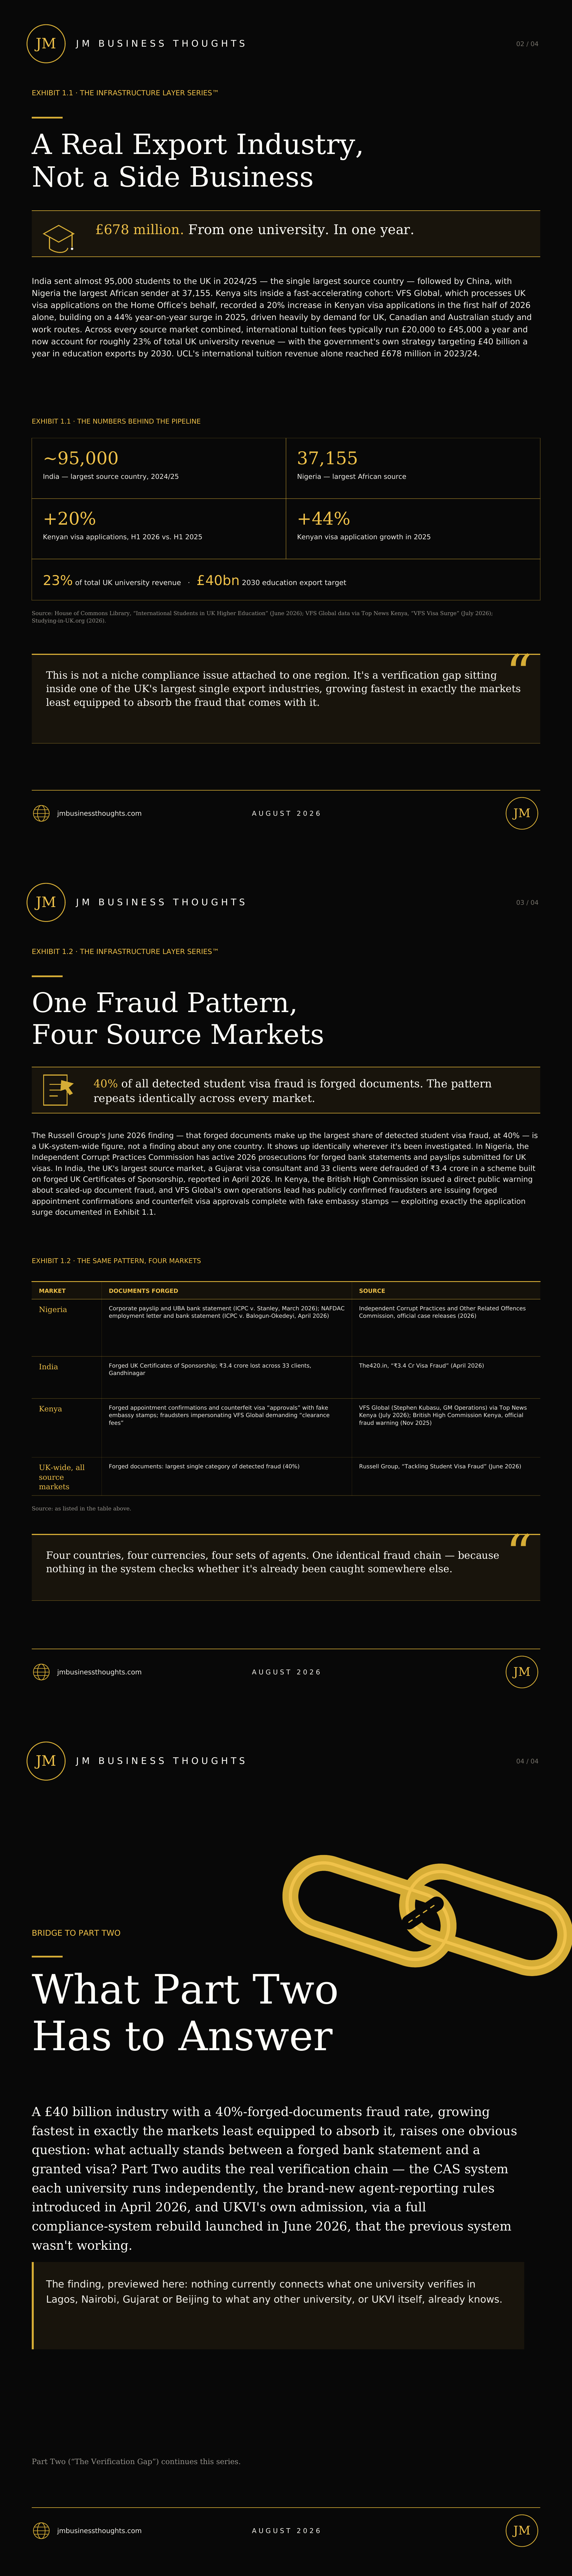
A real export industry, not a side business

The framing matters before the fraud numbers do. UK higher education sells a service internationally at a scale comparable with major manufactured-goods categories, and the government treats it as such: the official strategy targets £40 billion a year in education exports by 2030. International tuition typically runs £20,000 to £45,000 a year per student and now accounts for roughly 23% of total UK university revenue.

Concentration at the institutional level is extreme. UCL alone booked £678 million of international tuition revenue in 2023/24 — one university, one year, more than the annual turnover of most listed UK mid-caps. For a large number of institutions, international fee income is not a growth line; it is the line that closes the deficit on domestic teaching and research.

Source-market composition is equally concentrated. India sent almost 95,000 students in 2024/25, the single largest source country, followed by China. Nigeria is the largest African sender at 37,155. Kenya sits inside a fast-accelerating cohort: VFS Global, which processes UK visa applications on the Home Office's behalf, recorded a 20% increase in Kenyan applications in the first half of 2026 alone, on top of a 44% year-on-year surge across 2025.

Read those two facts together and the exposure becomes obvious. A revenue line worth a quarter of sector income depends on documentary evidence originating in jurisdictions where the underlying records — bank statements, payslips, employer letters, examination certificates — cannot be verified at source by the institution receiving them.

£678 million. From one university. In one year.
  • £40bn a year: the UK government's 2030 education export target
  • 23% of total UK university revenue now comes from international tuition
  • £20,000–£45,000 typical annual international fee
  • ~95,000 from India; 37,155 from Nigeria; Kenya +20% in H1 2026 after +44% in 2025
  • Sources: House of Commons Library, 'International Students in UK Higher Education' (June 2026); VFS Global via Top News Kenya (July 2026); Studying-in-UK.org (2026)
02

One fraud pattern, four source markets

The Russell Group's June 2026 finding is the anchor number: forged documents make up the largest single category of detected student visa fraud, at 40%. That is a UK-system-wide figure across all source markets — not a finding about any one country — and it describes detected fraud only, which is the subset that a fragmented, single-institution check managed to catch.

The same pattern surfaces identically wherever it has been investigated. In Nigeria, the Independent Corrupt Practices and Other Related Offences Commission carries active 2026 prosecutions built on forged bank statements, payslips and employer letters submitted for UK visas. In India, the UK's largest source market, a Gujarat visa consultant and 33 clients were defrauded of ₹3.4 crore in a scheme constructed around forged UK Certificates of Sponsorship.

In Kenya, the British High Commission issued a direct public fraud warning, and VFS Global's own general manager of operations has confirmed that fraudsters are issuing forged appointment confirmations and counterfeit visa approvals complete with fake embassy stamps — exploiting precisely the application surge documented above. Four countries, four currencies, four separate agent networks, one identical chain.

The uniformity is the finding. When the same fraud construction appears across markets with no shared language, banking system or agent population, the common factor is not the fraudster. It is the verification architecture they are all submitting into.

Four countries, four currencies, four sets of agents. One identical fraud chain.
  • 40%: forged documents as a share of all detected UK student visa fraud (Russell Group, June 2026)
  • Nigeria — ICPC v. Stanley (Mar 2026): corporate payslip and UBA bank statement
  • Nigeria — ICPC v. Balogun-Okedeyi (Apr 2026): NAFDAC employment letter and bank statement
  • India — ₹3.4 crore lost across 33 clients on forged Certificates of Sponsorship, Gandhinagar (Apr 2026)
  • Kenya — counterfeit visa approvals with fake embassy stamps; impersonation of VFS Global demanding 'clearance fees'
03

Why the same forgery works more than once

A university admissions team that rejects a fabricated bank statement produces valuable intelligence: a template, an issuing branch, a formatting artefact, an agent fingerprint. That intelligence is then stored in a case-management system visible to exactly one institution, and in most cases to exactly one team inside it.

No standardised mechanism exists for that signal to reach the other 100-plus institutions receiving applications from the same agent in the same intake cycle. The Confirmation of Acceptance for Studies system is administered institution by institution; UKVI sees the sponsorship record, not the underlying documentary evidence the institution assessed. The fraud economics follow directly: the cost of producing a forgery is incurred once, and the number of times it can be submitted is bounded only by the number of institutions in the market.

This asymmetry is what converts an individually competent system into a collectively failing one. Detection capability is genuinely high at the point of assessment — 40% of detected fraud being documentary is evidence that admissions teams find these things. What is absent is persistence and propagation of the finding.

In infrastructure terms, the sector has inspectors but no register. It performs the expensive part of the work — assessment — repeatedly, and discards the cheap, compounding part — shared memory — every single time.

Detection is not the gap. Memory is.
  • Forgery cost is incurred once; submission opportunities scale with institution count
  • CAS is administered per institution — no shared documentary-evidence layer
  • Rejection intelligence dies inside a single admissions case file
  • Agents operate across institutions; institutions do not operate across agents
04

Where the cost actually lands

The visible cost is fraud loss, but that is the smallest component. The larger, recurring cost is duplicated manual verification: every institution independently telephoning banks, emailing awarding bodies and commissioning third-party credential checks against the same documents, at the same time, for the same applicants.

The second-order cost is compliance risk. A sponsor licence is the licence to operate the export business itself; refusal-rate thresholds and compliance findings put that licence at risk. An institution's exposure therefore is not proportional to the fraud it catches but to the fraud it misses — an unbounded liability assessed against a bounded review budget.

The third cost is the one nobody prices: legitimate applicants from high-risk markets absorbing longer processing times, additional evidential demands and higher refusal probability because the system cannot distinguish them cheaply. Friction applied to a whole cohort is the standard substitute for intelligence about individuals.

Each of those three costs is measured today, by the buyer, in numbers the buyer already reports. That is what makes this vertical commercially legible rather than merely worthy.

Friction applied to a whole cohort is the standard substitute for intelligence about individuals.
  • Duplicated verification spend across 100+ institutions checking identical documents
  • Sponsor licence exposure: unbounded liability against a bounded review budget
  • Cohort-level friction imposed on legitimate applicants from surging markets
  • Agent oversight cost rising with the new April 2026 agent-reporting requirements
05

The shape of the missing layer

The mechanism required is narrow and unglamorous: a document is checked once, its cryptographic fingerprint and fraud verdict are written to a shared register, and every subsequent submission of that document — or of a near-identical template — is flagged instantly at any participating institution.

Nothing in that description requires frontier AI. It requires document fingerprinting, template-family clustering, an interoperable schema for verdicts, and an information-governance framework that lets competing institutions share fraud signals without sharing applicant data. The AI component sits on top: pattern recognition across templates, agent-network graph analysis, and anomaly detection on financial evidence that no individual reviewer would see because no individual reviewer sees the corpus.

The defensibility is network-shaped and therefore winner-takes-most. Each additional institution makes the register more valuable to the next, and the value of the corpus — years of accumulated forgery templates and agent fingerprints — is not replicable by a later entrant with better software.

The buyer is identifiable and already spending: admissions and compliance functions inside universities, sector bodies, and ultimately UKVI, which launched a full compliance-system rebuild in June 2026 — an implicit admission that the prior architecture was not working.

Check once, flag everywhere. The hard part is governance, not modelling.
  • Document fingerprinting plus template-family clustering across institutions
  • Shared verdict register with applicant data minimised by design
  • Agent-network graph analysis — the layer no single institution can build
  • Commercial model priced against duplicated verification spend already incurred
06

Sizing the pool: what the duplicated work actually costs

The addressable value is not the fraud loss. It is the recurring cost of every institution performing the same verification work in parallel, plus the compliance provision held against the fraud that slips through, plus the conversion lost to friction imposed on legitimate applicants.

Take the arithmetic conservatively. Roughly 120 UK institutions carry meaningful international recruitment. A mid-sized international admissions operation processes 6,000 to 14,000 overseas applications a cycle. Documentary verification — bank statements, transcripts, sponsorship and employer letters — absorbs between 25 and 55 minutes of qualified reviewer time per file once escalations, callbacks and third-party credential checks are included. At a fully loaded £32–£42 an hour, that is £1.1M–£3.4M of verification labour per large institution per cycle, before any external credential-checking fees.

Aggregated across the sector, documentary verification labour and third-party checking fees sit in a £180M–£320M annual band. A shared register does not remove that work; it removes its duplication. Where a document, template family or agent has already been adjudicated, the marginal cost of the second, third and eleventh assessment falls toward zero. Realistic dedupe rates of 30–45% on documentary review in the second full year imply £55M–£140M of recoverable annual cost across the sector.

Two further pools sit alongside it. Compliance provision — the internal cost of sponsor-licence assurance, audit response and refusal-rate remediation — runs at £40M–£90M sector-wide, of which a shared evidence trail addresses perhaps a third. And conversion: even a 1.5-point reduction in drop-out among low-risk applicants held in extended evidential review, priced at a £24,000 median fee, returns tens of millions in retained tuition. The infrastructure layer is therefore a £120M–£260M annual value pool against a build cost measured in single-digit millions.

£120M–£260M of annual recoverable value against a single-digit-million build.
  • ~120 institutions × 6,000–14,000 international applications per cycle
  • 25–55 reviewer-minutes per file fully loaded at £32–£42/hour
  • £180M–£320M sector-wide documentary verification labour and third-party fees
  • 30–45% dedupe on documentary review by Year 2 → £55M–£140M recoverable
  • Compliance provision £40M–£90M; addressable share approximately one third
  • Illustrative modelling of run-rate potential under stated assumptions, not a forecast
07

The five-year adoption and economics model

Network infrastructure is priced on density, not features. The model that matters is how quickly participating institutions reach the point where the register answers most queries — the crossover after which non-participation becomes the expensive option.

Year 1 is a consortium of 8–12 institutions concentrated in one mission group, seeded with historical rejection data rather than live traffic. Coverage of submitted documents is 6–10%; hit rate on repeat submissions is low but non-zero, and the deliverable is governance proof, not savings. Subscription pricing of £40,000–£90,000 per institution per year produces £0.5M–£1.0M of revenue against a £2.5M–£4M build.

Years 2 and 3 are the density years. At 35–60 institutions, coverage passes 40% of sector international volume and repeat-submission hit rates climb to 12–22% of flagged documents — the first period in which a member can evidence avoided reviewer hours in its own management accounts. Revenue reaches £3M–£7M, with gross margin above 70% because the corpus, not headcount, does the work.

Years 4 and 5 are the incumbency years. Beyond 80 institutions plus sector-body and regulator interfaces, the register is the default first check, agent analytics become a separately priced module, and source-market attestation partnerships convert the product from a defensive utility into a rail that others build on. Revenue of £9M–£18M at 75–82% gross margin, with cumulative member savings of £160M–£400M over the period — a payback ratio no individual institution can replicate alone.

The sensitivity that governs all of it is legal and cultural, not technical: how long competing institutions take to agree a data-sharing framework. Every quarter of governance delay pushes the density crossover out by roughly two quarters, because admissions cycles are annual and adoption decisions cluster.
Density, not features. The crossover is where non-participation becomes the expensive option.
  • Year 1 — 8–12 institutions, 6–10% document coverage, £0.5M–£1.0M revenue, £2.5M–£4M build
  • Years 2–3 — 35–60 institutions, 40%+ volume coverage, £3M–£7M revenue, >70% gross margin
  • Years 4–5 — 80+ institutions plus regulator interface, £9M–£18M revenue, 75–82% margin
  • Cumulative member savings £160M–£400M across the five-year window
  • Governance latency is the dominant sensitivity: one quarter of delay ≈ two quarters of crossover slippage
08

Build sequence: five phases to the default check

Phase 1 — Governance first (months 0–6). Information-sharing framework, lawful basis, data-minimisation design and a competition-safe consortium structure agreed before a line of production code. This phase kills more infrastructure ventures than engineering ever does.

Phase 2 — Corpus seeding (months 4–12). Ingest historical rejection records from founding members, fingerprint documents, cluster template families and establish a verdict schema with versioning and appeal. The asset being built here is the corpus, not the interface.

Phase 3 — Live intake integration (months 9–18). Straight-through integration into admissions and CRM systems at founding members, with flag-at-submission latency measured in seconds and a documented human-review override on every automated verdict.

Phase 4 — Agent and financial rails (months 15–30). Agent-network graph analytics layered on the corpus, open-banking and bank-confirmation channels in the four priority source markets, and attestation caching with awarding bodies.

Phase 5 — Regulator interface and scale (months 24–60). Machine-readable aggregate intelligence published to UKVI, alignment with the June 2026 compliance rebuild, and sector-body endorsement that converts a subscription product into standard practice.

  • Phase 1 · Governance and consortium structure — months 0–6
  • Phase 2 · Corpus seeding and template clustering — months 4–12
  • Phase 3 · Live intake integration and flag-at-submission — months 9–18
  • Phase 4 · Agent graph analytics and financial verification rails — months 15–30
  • Phase 5 · Regulator interface, sector endorsement and scale — months 24–60
09

Governance, fairness and the assumptions this rests on

A shared fraud register is a powerful instrument aimed at individuals with limited recourse, and it must be built as such. Three design constraints are non-negotiable. Store hashes and verdicts, not applicant documents. Attach every automated flag to a named human decision-maker. And provide a documented appeal route with the ability to expunge an incorrect verdict from the corpus and from downstream members.

The fairness risk is concentrated and predictable: template-family clustering will over-index on documents originating from particular banks, examination boards and regions, because that is where volume and standardisation coincide. Without deliberate calibration, the register becomes a nationality proxy — which is both unlawful and commercially fatal for a sector body. Ongoing bias auditing by source market, with published false-positive rates, is a product requirement rather than a compliance afterthought.

The model assumes stable or growing international student volumes, no mandated central verification register displacing the private layer, sustained sponsor-licence enforcement, and a workable consortium data-sharing agreement. Remove any of the four and the economics change materially rather than marginally.

Priced honestly, the downside case is not failure but delay: governance friction pushes density out two to three years, revenue compresses toward the low band, and the corpus advantage still accrues to whoever holds it. The upside case is a regulated utility with private economics and a decade of accumulated forgery intelligence nobody can rebuild.

Store hashes, not people. Every flag needs a human owner and an appeal route.
  • Data minimisation by design — hashes and verdicts, never stored applicant documents
  • Human decision-maker attached to every automated flag; documented appeal and expungement
  • Published false-positive rates by source market to prevent nationality-proxy drift
  • Assumptions: stable volumes, no mandated state register, sustained enforcement, workable data-sharing agreement
  • Downside case is delay, not failure — the corpus advantage compounds regardless
10

What would break the thesis — and what Part Two answers

Three things would break it. First, UKVI's June 2026 compliance rebuild extends into a mandated central verification register, collapsing the addressable market to integration services. Second, information-governance friction between competing institutions proves slower than the admissions cycle, so no operator reaches the density at which the register becomes the default answer. Third, a policy-driven contraction in international student numbers shrinks the value pool faster than the layer can be built.

Of the three, the second is the most likely and the most survivable: it delays rather than eliminates, and it is precisely the failure mode a sector body or consortium structure is designed to absorb.

Part Two — 'The Verification Gap' — audits the real chain that currently stands between a forged bank statement and a granted visa: the CAS system each university runs independently, the agent-reporting rules introduced in April 2026, and UKVI's own compliance-system rebuild launched in June 2026.

The finding, previewed here: nothing currently connects what one university verifies in Lagos, Nairobi, Gujarat or Beijing to what any other university, or UKVI itself, already knows.

  • Watch: scope of the UKVI compliance-system rebuild announced June 2026
  • Watch: enforcement of the April 2026 agent-reporting requirements
  • Watch: quarterly visa refusal rates by source market
  • Watch: any sector-body move toward a shared fraud register
  • Watch: Kenyan and Nigerian application volumes against BHC fraud warnings

The Multiplier Framework

7 compounding levers

Six infrastructure positions sit inside a single admissions pipeline. Each is separately fundable, each has a buyer already carrying the cost manually, and each compounds the others: fingerprinting creates the corpus, the corpus powers agent analytics, and the analytics justify the network.

01

Shared Document Fraud Register

Check once, flag everywhere

  • Fingerprint every submitted financial and academic document at intake
  • Write verdicts to a shared register visible to all participating institutions
  • Cluster near-identical forgeries into template families automatically
  • Minimise applicant data by storing hashes and verdicts, not documents

Outcome · A rejected forgery stops working at institution two, not institution five

02

Agent Network Graph Analytics

See the operator behind the applications

  • Link applications to agents, sub-agents and referral chains across institutions
  • Score agent portfolios on forgery incidence and refusal outcomes
  • Feed the April 2026 agent-reporting obligation from the same data spine
  • Escalate coordinated submission bursts across multiple universities

Outcome · Oversight of the distribution channel, not just the individual applicant

03

Financial Evidence Verification Rail

Verify funds at source instead of on paper

  • Integrate open-banking and bank-confirmation channels in key source markets
  • Detect statement-template anomalies against known-good institutional formats
  • Flag balance-seasoning and borrowed-funds patterns statistically
  • Standardise the maintenance-funds evidence schema across institutions

Outcome · Forged bank statements lose their economic value as an input

04

Credential Attestation Exchange

One authoritative answer per certificate

  • Connect awarding bodies and examination boards in top source markets
  • Cache verified qualification attestations for reuse across applications
  • Version and timestamp attestations for audit and appeal
  • Retire duplicate third-party credential checks on the same document

Outcome · Duplicated verification spend collapses toward a single check per credential

05

Risk-Tiered Admissions Triage

Spend review hours where the risk actually is

  • Score applications on documentary risk before manual review is allocated
  • Fast-track low-risk applicants from high-volume surging markets
  • Route high-risk files to specialist review with the evidence attached
  • Report reviewer-hours saved per intake against the compliance budget

Outcome · Faster offers for legitimate students without widening the fraud gap

06

Cross-Border Regulator Interface

Make the register legible to UKVI and source-market authorities

  • Publish aggregate fraud-pattern intelligence to UKVI in a machine-readable form
  • Align with the June 2026 compliance-system rebuild rather than around it
  • Support ICPC-style prosecutions with structured, exportable evidence
  • Give High Commissions live template intelligence for public fraud warnings

Outcome · Sector-level fraud intelligence becomes a regulated public good with a private operator

07

Assurance & Audit Trail Layer

Make every verdict defensible

  • Version, timestamp and attribute every automated flag to a named reviewer
  • Provide applicant appeal and expungement with downstream propagation
  • Publish false-positive rates by source market to prevent proxy discrimination
  • Package the evidence trail for sponsor-licence audit and Home Office inspection

Outcome · Sponsor-licence assurance cost falls while fairness exposure is actively priced

International Student Credential & Financial Verification — Part One: The Scale & The Fraud full strategic breakdown
The Infrastructure Layer Series™ · Part One of Three — the full report: Exhibit 1.1 (the numbers behind the pipeline), Exhibit 1.2 (the same fraud pattern across four source markets) and the bridge to Part Two, 'The Verification Gap'.

The Verdict

A £40 billion export industry is being defended by 100-plus institutions each solving the same verification problem alone, and each forgetting what it learned the moment the file closes. The fraud is not sophisticated — forged bank statements, fabricated certificates, counterfeit sponsorship letters — it is simply reusable, because nothing connects one rejection to the next application. That is the definition of a missing infrastructure layer: high aggregate cost, identifiable buyers, no capital barrier, and no owner. Part Two audits the chain that is supposed to be stopping it.

JM founder signature
68 · PureGym — Fitness At Scale. More Personal. More Inclusive.67 · SIXT — Smarter Mobility. Greater Availability. A More Connected Tomorrow.66 · Sendwave — Money That Moves With Intelligence.65 · McDonald’s — Serving The Future With AI.64 · Compare the Market — Smarter Comparison. Better Matches. Brighter Tomorrows.63 · WeBuyAnyCar — Smarter Pricing. Faster Offers. Better Conversion.62 · Primark — Affordable Fashion. Greater Possibilities With AI.61 · Starbucks — Smarter Stores. Stronger Loyalty. Better Margins.60 · IKEA — AI-Powered Home Retail at Global Scale59 · H&M — Smarter Fashion. Brighter Tomorrow.58 · WeWork — The Value Wasn't Lost. It Was Mispriced.57 · Yahoo — The Value Wasn't Lost. It Was Mispriced.56 · Nando's UK — Smarter Restaurants. Stronger Loyalty. Better Margins.55 · The Amplifier54 · The Body Shop53 · Arcadia Group52 · Cazoo51 · Blockbuster50 · Carpetright49 · Wilko48 · Mothercare47 · Phones 4u46 · Farfetch45 · Jumia44 · Toys ‘R’ Us43 · The Collateral Gap — Part One41 · The Amplifier40 · Africa Bee Farming39 · Kenya Airways38 · Africa Greenhouse Farming37 · Uganda Tourism Board36 · Boots UK35 · Biffa (UK)34 · NatWest33 · Skip Hire Companies UK33 · The Audit32 · The Lean Company31 · Africa Mushroom Farming29 · The Rider Economy Nobody Verified28 · The Layer Underneath the Layer27 · Independent Timber Yards & Jewson Timber26 · Link Up TV & GRM Daily25 · East African Portland Cement23 · The White Space, Mapped22 · The Real Opportunity21 · Greencore20 · West Ham United19 · Roofings Group Uganda18 · Mombasa Port17 · Auto Trader UK16 · Uganda Coffee Development Authority15 · Brookside Dairy14 · GraceKennedy13 · Rightmove12 · Manchester United11 · Greggs30 · Twiga Foods10 · Uchumi09 · Konga08 · Edcon09 · GAME07 · Debenhams06 · Claire's05 · Boohoo04 · Argos