The Amplifier: Part One — The Thesis: Why the Beat Could Shift research poster
All Research

The Amplifier™

Can AI Make East Africa Africa's Next Music & Events Powerhouse?

41The Amplifier™ · Part One 16 min readAugust 2026
Coverage · East Africa · Kenya · Tanzania · Uganda · Institutional CoverageSector · Music, Live Events & Creative InfrastructureFormat · Six-page audit

The AmplifierThree Major Labels Chose Nairobi In One Meeting. That Is A Dated Bet, Not A Vibe.

Part One of The Amplifier™ sets the thesis: the studio-infrastructure moat that made Lagos and Johannesburg the only places you could reliably sound professional is eroding — for everyone at once. Sony, Universal and Warner all committed to Nairobi on 21 July 2026, against a listener base where 18–24s are 53.7% of city streams. The prize is not who discovers AI first; it is who builds the labels, festivals and distribution around cheaper production first.

South Africa Revenue Share

77–78%

Amapiano Value (2024)

$120M+

Afrobeats Streams (2023)

13.5B

Nairobi Gen Z Stream Share

53.7%

Lagos / Joburg Gen Z Share

44.4% / 29.9%

Amapiano Producer AI Adoption

50% in 2 yrs

Dancehall Growth (Kenya, YoY)

+95%

Major Labels Committing To Nairobi

3 of 3

The Thesis

For two decades, the binding constraint on African recorded music was not talent — it was the cost of sounding professional. Studios, engineers and mastering capacity clustered in Lagos and Johannesburg, and the revenue clustered with them: 77–78% of Sub-Saharan recorded music revenue still sits in one country. AI production tooling collapses that constraint, but it collapses it for everybody simultaneously — which means the moat is not transferring, it is dissolving. In a dissolved-moat market, the winner is whoever assembles the surrounding infrastructure — labels, rights administration, festivals, ticketing and distribution — fastest. On 21 July 2026, three profit-driven multinationals placed a simultaneous, dated bet that this infrastructure gets built in Nairobi. Part One argues why that bet is plausible. Part Two tests whether it is earned.

Exhibit · Report Cover

41 · The Amplifier™ · Part One

The Amplifier: Part One — The Thesis: Why the Beat Could Shift report cover
The Amplifier: Part One — The Thesis: Why the Beat Could ShiftAugust 2026 · East Africa · Kenya · Tanzania · Uganda · Institutional Coverage
01

Executive summary: a plausible thesis, not a verdict

Three weeks before publication, Sony Music, Universal Music Group and Warner Music Group each agreed to establish a presence in Nairobi following a meeting convened with IFPI CEO Victoria Oakley and announced by President William Ruto. Three competitors reaching the same conclusion in the same week is a signal about expected future cash flows, not about cultural sentiment.

The economic logic underneath it is a cost collapse. Professional-grade production — tracking, mixing, mastering, stem separation, vocal cleanup — is moving from a capital expense concentrated in two cities to a marginal-cost software function available anywhere with bandwidth. When the capital barrier falls, geography stops being a filter and infrastructure becomes the differentiator.

This brief takes the deliberately unpopular position that the disruption is symmetric. Amapiano producers are projected to reach 50% AI-tool adoption within two years; Nigerian artists are already adopting AI production specifically to cut costs. East Africa does not get a secret weapon. It gets a level playing field — and a narrow window in which to build the commercial layer before the incumbents do.
The moat is not moving north. It is disappearing for everyone at once — which is a different, and much harder, competition.
  • Signal: 3 of 3 majors commit to Nairobi in a single meeting, 21 July 2026
  • Structural: production cost collapse removes the two-city bottleneck
  • Demographic: Nairobi's 18–24s are 53.7% of city Spotify streams
  • Caveat: incumbent AI adoption is running ahead, not behind
02

Exhibit 1.1 — The incumbents' scoreboard

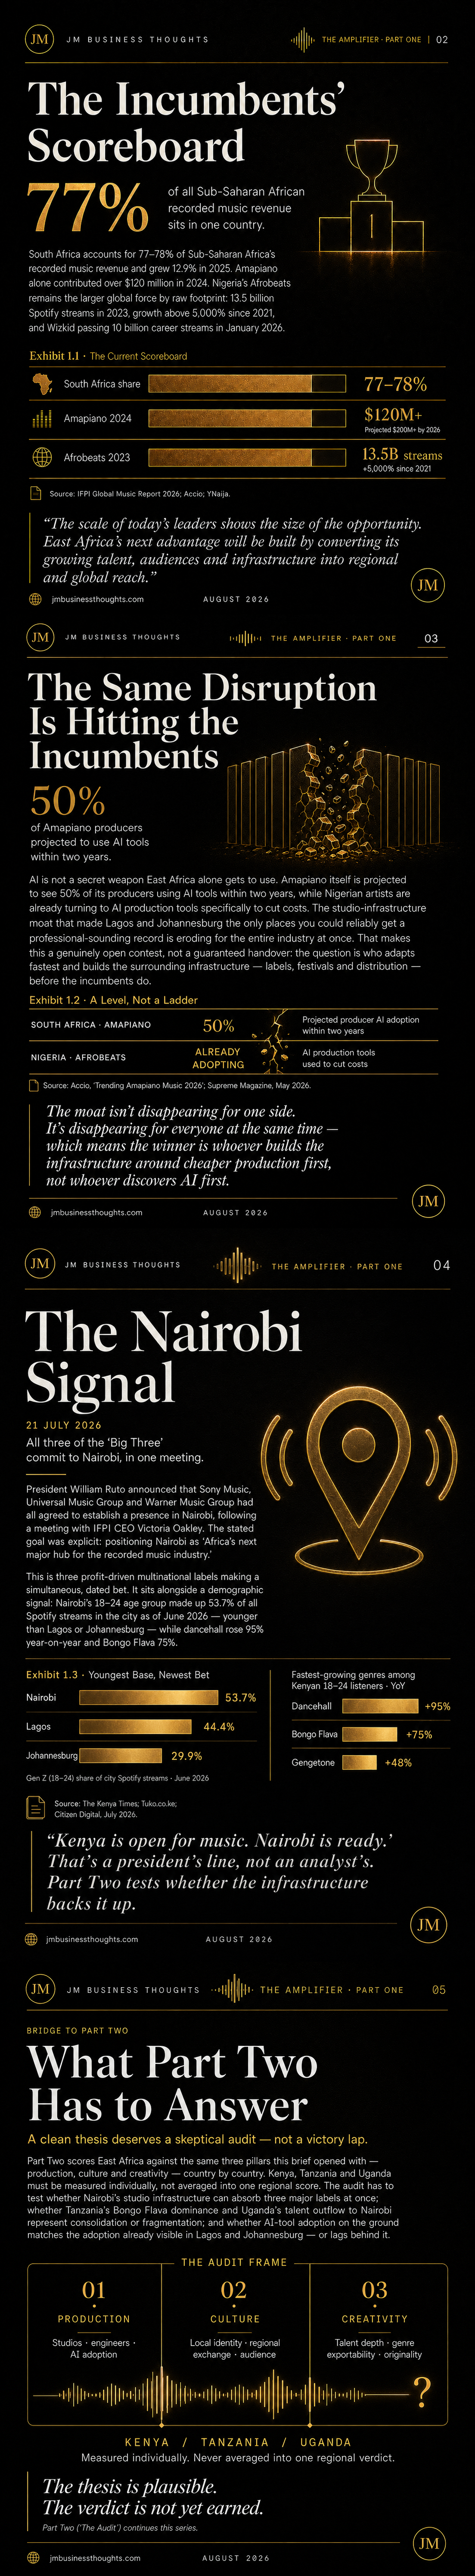
South Africa accounts for 77–78% of Sub-Saharan Africa's recorded music revenue and grew 12.9% in 2025. Amapiano alone contributed over $120 million in 2024, with projections above $200M by 2026. Nigeria's Afrobeats remains the larger global force by raw footprint: 13.5 billion Spotify streams in 2023, growth above 5,000% since 2021, and Wizkid passing 10 billion career streams in January 2026.

Read correctly, these are not intimidation numbers — they are addressable-market numbers. They demonstrate that African-origin catalogue can carry global monetisation at scale, which is the precondition any challenger market needs before capital will underwrite it.

The concentration also exposes the vulnerability. A market where three-quarters of revenue sits in one country is a market whose infrastructure, not its audience, is doing the concentrating. Change the infrastructure economics and the distribution of revenue becomes contestable.

77% in one country is not a wall. It is evidence that the ceiling is high and the floor is unevenly built.
  • South Africa: 77–78% of SSA recorded music revenue; +12.9% in 2025
  • Amapiano: $120M+ in 2024, projected $200M+ by 2026
  • Afrobeats: 13.5B Spotify streams (2023); +5,000% since 2021
  • Source: IFPI Global Music Report 2026; Accio; YNaija
03

Exhibit 1.2 — A level, not a ladder

The seductive version of this thesis is that AI hands East Africa a weapon its rivals lack. The evidence does not support it. Amapiano is projected to see 50% of its producers using AI tools within two years, and Nigerian artists are already turning to AI production tools explicitly to cut costs.

What is actually happening is the simultaneous erosion of a shared moat. The studio-infrastructure advantage that made Lagos and Johannesburg the only reliable route to a professional record is degrading for the entire industry at the same moment.

That reframes the competitive question. It is no longer 'who gets AI?' — everyone does. It is 'who converts cheaper production into owned rights, repeatable release calendars, live revenue and export routes before the advantage is competed away?' That is an execution contest, and execution contests are won by infrastructure, not by novelty.

Whoever builds the infrastructure around cheaper production wins — not whoever discovers AI first.
  • South Africa · Amapiano: 50% projected producer AI adoption within two years
  • Nigeria · Afrobeats: AI production tools already in use to cut costs
  • Implication: no first-mover advantage on tooling — only on commercialisation
  • Source: Accio, 'Trending Amapiano Music 2026'; Supreme Magazine, May 2026
04

Exhibit 1.3 — The Nairobi signal

On 21 July 2026, President William Ruto announced that Sony Music, Universal Music Group and Warner Music Group had all agreed to establish a presence in Nairobi, following a meeting with IFPI CEO Victoria Oakley. The stated goal was explicit: positioning Nairobi as 'Africa's next major hub for the recorded music industry.'

Alongside it sits a demographic signal that is harder to manufacture. Nairobi's 18–24 cohort made up 53.7% of all Spotify streams in the city as of June 2026 — younger than Lagos at 44.4% and Johannesburg at 29.9%. Dancehall rose 95% year-on-year among Kenyan 18–24 listeners, Bongo Flava 75% and Gengetone 48%.

A younger streaming base matters commercially for three reasons: it lengthens the monetisable lifetime of any catalogue signed today, it raises the ceiling on live and merchandise attach rates, and it makes the market attractive to brand partners whose media budgets follow that exact cohort.

'Kenya is open for music. Nairobi is ready.' That is a president's line, not an analyst's. Part Two tests whether the infrastructure backs it up.
  • Gen Z (18–24) share of city Spotify streams, June 2026: Nairobi 53.7% · Lagos 44.4% · Johannesburg 29.9%
  • Fastest-growing genres among Kenyan 18–24s: Dancehall +95% · Bongo Flava +75% · Gengetone +48%
  • Three majors, one meeting, one dated commitment
  • Source: The Kenya Times; Tuko.co.ke; Citizen Digital, July 2026
05

Where the money actually sits: the events layer

Recorded music is the headline; live events are the margin. In markets with low streaming ARPU and high piracy leakage, the reliable cash line is ticketing, sponsorship, hospitality and touring — all of which are geographically captive and therefore defensible in a way that a stream is not.

East Africa's structural advantage in this layer is under-discussed: a dense corridor of three capitals within a short-haul flight of each other, a shared regional audience, and a festival calendar that is still unconsolidated — meaning promoters can be aggregated rather than displaced.

AI's contribution here is unglamorous and highly bankable: demand forecasting for pricing tiers, fraud and duplicate-ticket detection, dynamic sponsorship valuation from measured attention, and routing optimisation that turns three one-off shows into a repeatable regional tour block.

A stream can be captured by anyone. A stadium cannot be relocated.
06

What has to be true for the thesis to hold

Rights administration must exist in a form international capital recognises. Without functioning collection, split management and dispute resolution, catalogue cannot be underwritten and label presence stays representational rather than operational.

Production capacity must absorb three majors at once. A label office does not create engineers, mastering capacity or A&R depth; it consumes them. If Nairobi's studio layer cannot scale headcount, signings will simply be exported for finishing — which reproduces the existing dependency.

Regional exchange must consolidate rather than fragment. Uganda's talent outflow to Nairobi and Tanzania's Bongo Flava dominance can either compound into one regional market or split into three sub-scale ones. Averaging Kenya, Tanzania and Uganda into a single score would hide exactly the variable that decides the outcome.

  • Rights & collections infrastructure that survives institutional diligence
  • Studio and engineering headcount that scales with label demand
  • Regional consolidation across Kenya, Tanzania and Uganda — measured separately
  • AI adoption on the ground matching, not lagging, Lagos and Johannesburg
07

Bridge to Part Two — the audit frame

A clean thesis deserves a skeptical audit, not a victory lap. Part Two scores East Africa against the same three pillars this brief opened with — production, culture and creativity — country by country.

Pillar 01 · Production covers studios, engineers and AI adoption. Pillar 02 · Culture covers local identity, regional exchange and audience. Pillar 03 · Creativity covers talent depth, genre exportability and originality.

Kenya, Tanzania and Uganda are measured individually and never averaged into one regional verdict. The audit tests whether Nairobi's studio infrastructure can absorb three major labels at once; whether Uganda's talent outflow and Tanzania's Bongo Flava dominance represent consolidation or fragmentation; and whether ground-level AI adoption matches what is already visible in Lagos and Johannesburg — or lags behind it.

The thesis is plausible. The verdict is not yet earned.

The Multiplier Framework

7 compounding levers

Seven value multipliers convert a production-cost collapse into a durable regional music and events economy. Each is scored on the commercial mechanism, the moves required and the outcome that makes it defensible.

01

Production Cost Collapse

Turn studio scarcity into a software line item.

  • Deploy AI tracking, mixing, mastering and stem-separation stacks in shared regional hubs
  • Certify engineers on AI-assisted workflows so quality is repeatable, not incidental
  • Price finishing services regionally to stop export of post-production to Lagos and Joburg

Outcome · Cost per broadcast-ready master falls by an order of magnitude; release volume scales without capex.

02

Rights & Catalogue Ownership

Own the asset, not just the moment.

  • Build split management, metadata hygiene and collection infrastructure to institutional standard
  • Use AI matching to recover unclaimed royalties across DSPs and broadcast
  • Structure regional catalogue vehicles that international capital can underwrite

Outcome · Catalogue becomes a financeable asset class rather than an unbanked income stream.

03

Audience & Demand Intelligence

Sign, release and tour against measured demand.

  • Instrument streaming, social and ticketing signals into one regional demand model
  • Predict genre momentum — Dancehall +95%, Bongo Flava +75%, Gengetone +48% — before it prices in
  • Target the 53.7% Gen Z Nairobi cohort with cohort-specific release strategy

Outcome · A&R and release timing shift from instinct to evidence, raising hit rate per pound deployed.

04

Live Events & Ticketing Economics

Capture the margin that cannot be streamed.

  • AI demand forecasting for tiered pricing and inventory release
  • Fraud, duplicate and resale detection to protect gate revenue
  • Route optimisation across Nairobi–Dar–Kampala to build repeatable tour blocks

Outcome · Higher sell-through, lower leakage and a regional touring circuit with predictable economics.

05

Export & Distribution Routing

Move regional genres into global playlists deliberately.

  • Automate localisation, metadata and territory targeting for DSP submission
  • Build diaspora-first launch corridors into the UK, Gulf and US markets
  • Track cross-border conversion to reallocate marketing spend weekly

Outcome · Export becomes a managed pipeline instead of an occasional viral accident.

06

Talent Retention & Regional Consolidation

Stop exporting artists and engineers as a default.

  • Fund studio and engineering headcount ahead of label demand, not after it
  • Create Uganda–Tanzania–Kenya co-production and co-release structures
  • Offer contract terms benchmarked against international standards

Outcome · Talent outflow converts into regional consolidation rather than permanent leakage.

07

Authenticity & Provenance Verification

Prove what is human, licensed and cleared.

  • Watermark and log AI involvement across the production chain
  • Automate sample clearance and likeness/voice consent records
  • Publish machine-readable provenance to DSPs, brands and broadcasters

Outcome · Brand and platform partners can transact at scale without legal ambiguity — a hard commercial moat.

The Amplifier: Part One — The Thesis: Why the Beat Could Shift full strategic breakdown
The Amplifier™ Part One — full brief: The Incumbents' Scoreboard, A Level Not a Ladder, The Nairobi Signal and the Part Two audit frame.

The Verdict

The thesis is plausible and the signal is real: three majors, one meeting, one dated commitment, against the youngest streaming base of Africa's three candidate hubs. But the advantage on offer is not AI — it is the commercial infrastructure built around a cost collapse that every rival is experiencing simultaneously. East Africa's window is the gap between tooling parity and infrastructure maturity, and that window is measured in months, not years. The verdict is not yet earned. Part Two audits it.

JM founder signature
68 · PureGym — Fitness At Scale. More Personal. More Inclusive.67 · SIXT — Smarter Mobility. Greater Availability. A More Connected Tomorrow.66 · Sendwave — Money That Moves With Intelligence.65 · McDonald’s — Serving The Future With AI.64 · Compare the Market — Smarter Comparison. Better Matches. Brighter Tomorrows.63 · WeBuyAnyCar — Smarter Pricing. Faster Offers. Better Conversion.62 · Primark — Affordable Fashion. Greater Possibilities With AI.61 · Starbucks — Smarter Stores. Stronger Loyalty. Better Margins.60 · IKEA — AI-Powered Home Retail at Global Scale59 · H&M — Smarter Fashion. Brighter Tomorrow.58 · WeWork — The Value Wasn't Lost. It Was Mispriced.57 · Yahoo — The Value Wasn't Lost. It Was Mispriced.56 · Nando's UK — Smarter Restaurants. Stronger Loyalty. Better Margins.55 · The Amplifier54 · The Body Shop53 · Arcadia Group52 · Cazoo51 · Blockbuster50 · Carpetright49 · Wilko48 · Mothercare47 · Phones 4u46 · Farfetch45 · Jumia44 · Toys ‘R’ Us43 · The Collateral Gap — Part One39 · Kenya Airways38 · Africa Greenhouse Farming37 · Uganda Tourism Board36 · Boots UK35 · Biffa (UK)34 · NatWest33 · Skip Hire Companies UK33 · The Audit32 · The Lean Company31 · Africa Mushroom Farming29 · The Rider Economy Nobody Verified28 · The Layer Underneath the Layer27 · Independent Timber Yards & Jewson Timber26 · Link Up TV & GRM Daily25 · East African Portland Cement42 · International Student Credential & Financial Verification — Part One24 · The Supply Chain Inside the Supply Chain23 · The White Space, Mapped22 · The Real Opportunity21 · Greencore20 · West Ham United19 · Roofings Group Uganda18 · Mombasa Port17 · Auto Trader UK16 · Uganda Coffee Development Authority15 · Brookside Dairy14 · GraceKennedy13 · Rightmove12 · Manchester United11 · Greggs30 · Twiga Foods10 · Uchumi09 · Konga08 · Edcon09 · GAME07 · Debenhams06 · Claire's05 · Boohoo04 · Argos