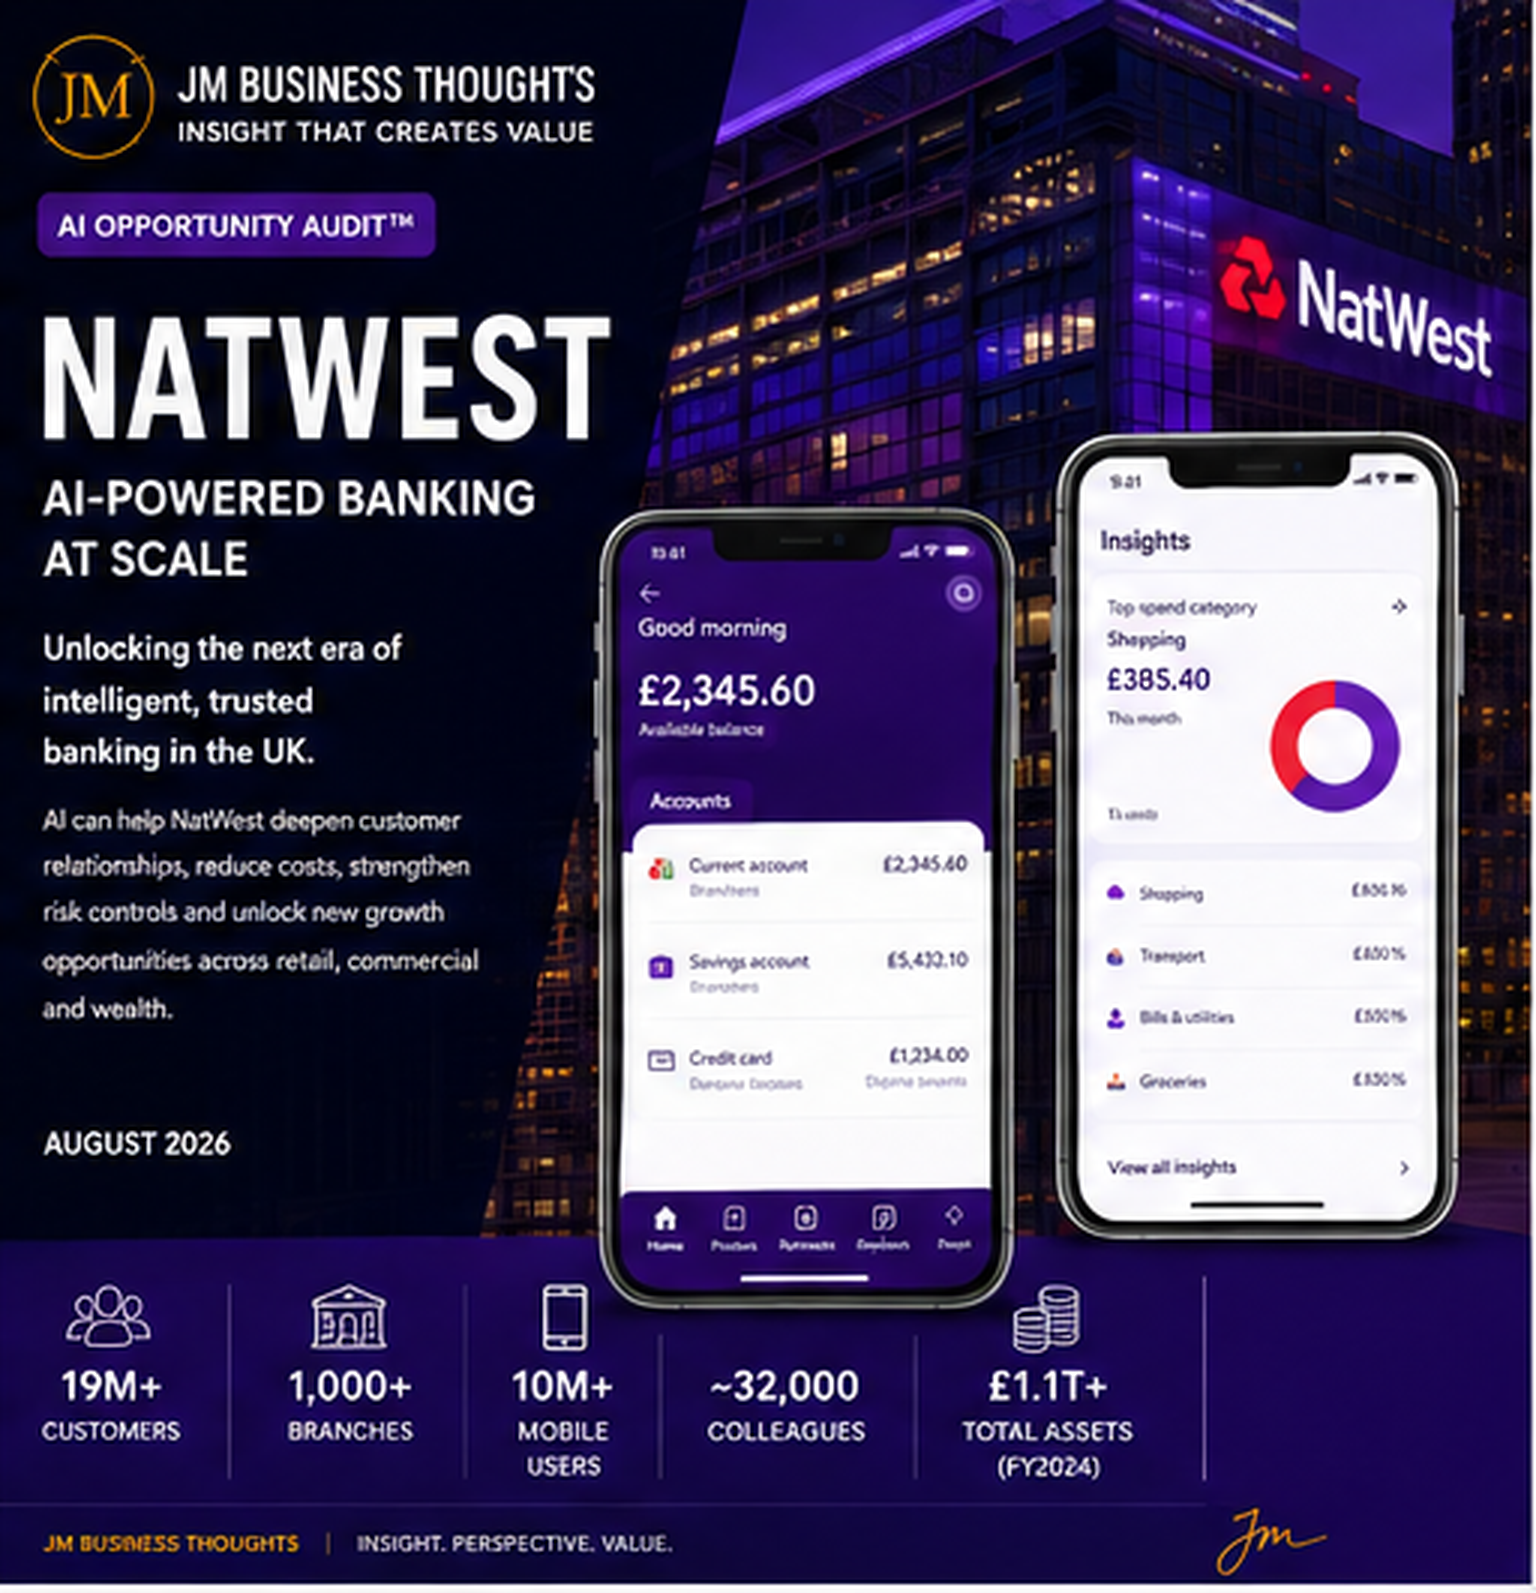
NatWest: AI-Powered Banking At Scale. research poster
All Research

The Hidden AI Operating System Audit Series™

Where AI creates new profit pools—not just productivity.

34AI Opportunity Audit™ 18 min readAugust 2026
Coverage · United Kingdom · Institutional CoverageSector · Banking · Retail, Commercial & WealthFormat · Six-page audit

NatWestUnlocking The Next Era Of Intelligent, Trusted Banking In The UK.

An AI Opportunity Audit™ across NatWest's retail, commercial and wealth franchises — customer experience, lending and credit, fraud and risk, operations automation, data monetisation and SME growth — identifying £1.1BN – £1.8BN of annual value potential by 2030.

Customers

19M+

Branches

1,000+

Mobile Users

10M+

Colleagues

~32,000

Total Assets (FY2024)

£1.1T+

Operating Profit (FY2024)

£6.2BN

S&P Credit Rating

AA− (Stable)

Annual AI Value By 2030

£1.1BN – £1.8BN

The Thesis

NatWest is not short of customers, capital or distribution. It is short of the operating layer that converts 19M+ relationships and £1.1T+ of assets into differentiated economics. UK banking is facing margin pressure, a rising cost of risk and customers who now benchmark their bank against Monzo and Revolut rather than Lloyds and Barclays. AI is the only lever that moves cost-to-income, credit quality and revenue growth simultaneously. Embedded across customer experience, operations, risk and commercial growth, it is worth £1.1BN – £1.8BN in annual value by 2030 — and the bank that executes it at scale leapfrogs peers rather than matching them.

Exhibit · Report Cover

34 · AI Opportunity Audit™

NatWest: AI-Powered Banking At Scale. report cover
NatWest: AI-Powered Banking At Scale.August 2026 · United Kingdom · Institutional Coverage
01

Executive summary: scale is the asset, execution is the constraint

NatWest enters the AI cycle from a position of unusual strength: 19M+ customers, 10M+ mobile users, £1.1T+ of total assets, £6.2BN of FY2024 operating profit and an AA− (stable) credit rating. Very few institutions can pair that balance sheet with that level of digital reach.

The value at stake is not a productivity story. It is a repricing of four line items: cost optimisation (£400M – £600M), risk and fraud reduction (£200M – £350M), revenue growth (£400M – £650M) and capital and balance sheet efficiency (£100M – £200M).

Aggregated, that is £1.1BN – £1.8BN of annual value by 2030 — material against a £6.2BN operating profit base, and achievable without a single acquisition.

£1.1BN – £1.8BN of total AI-driven value potential per year by 2030.
  • Cost optimisation: £400M – £600M (process automation, back-office efficiency)
  • Risk & fraud reduction: £200M – £350M (fraud detection, credit risk, compliance)
  • Revenue growth: £400M – £650M (personalisation, cross-sell, SME and digital growth)
  • Capital & balance sheet: £100M – £200M (better risk modelling, capital optimisation)
02

Market overview: a £283BN sector growing at ~2%

UK banking generated roughly £283BN of revenue in 2024 and is forecast to grow at only ~2% through 2030. In a low-growth pool, share and margin — not market expansion — determine who wins.

Average cost-to-income across the sector sits near 10% below where digital-first challengers operate, and ~60% of customers now say they are open to AI-generated financial advice. Demand-side permission is no longer the blocker.

The competitive set splits cleanly. Lloyds, HSBC and Barclays are scaling AI from similar legacy estates. Monzo and Revolut are AI-native, with no core migration cost and no branch drag. NatWest's advantage is that it can pair challenger-grade experience with a systemic balance sheet — if it moves before the gap becomes structural.

~60% of UK customers are already open to AI-generated financial advice.
  • UK banking revenue (2024): £283BN
  • Revenue growth (2024–2030E): ~2%
  • Average cost-to-income ratio: ~10% improvement opportunity
  • Competitive set: Lloyds, HSBC, Barclays, Monzo, Revolut
03

AI maturity snapshot: strong foundation, significant upside

Across four dimensions, the audit scores NatWest as advancing rather than leading. Data and analytics is the strongest position — a strong data foundation with scaling advanced analytics. AI capabilities are mid-maturity, with growing in-house capability supported by partner ecosystems.

Culture and talent is investing but incomplete: AI skills and change enablement remain the rate-limiting factor in most large-bank programmes, not model availability. Technology is migrating to cloud and modernising core systems, which is the precondition for anything else scaling.

Overall: a strong foundation with significant upside. The institutions that convert this position into leadership do so by industrialising deployment — not by running more pilots.

  • Data & analytics: strong foundation, scaling advanced analytics
  • AI capabilities: growing in-house capability, partner ecosystem
  • Culture & talent: investing in AI skills and change enablement
  • Technology: cloud migration and core system modernisation underway
04

The financial impact model: base year to Year 5

The illustrative model runs a full AI transformation over five years. Revenue moves from £16.0BN in the FY2024 base to £18.8BN by Year 5, with gross margin lifting from 52% to 57% and EBITDA margin from 26% to 31%.

Cost-to-income — the single number the market prices — falls from 62% to 48%, a 14-point compression that is worth more to the equity story than the revenue uplift itself. EPS moves from 38.2p to 63.8p over the same horizon.

Cumulative value creation over five years breaks into cost savings of £600M – £1.0BN+ (15–20%), revenue uplift of £600M – £1.0BN+ (10–15%) and risk and fraud reduction of £200M – £400M+ — a total value opportunity of £1.4BN – £2.4BN.

Cost-to-income from 62% to 48% — the number the market actually prices.
  • Revenue: £16.0BN → £18.8BN
  • Gross margin: 52% → 57%
  • EBITDA margin: 26% → 31%
  • EPS: 38.2p → 63.8p
05

Assumptions and risk envelope

The model assumes a moderate economic environment, AI adoption phased over three to five years, no major regulatory shock, continued investment in technology and data, and stable credit conditions.

Downside risks are concentrated in three places: model governance and FCA scrutiny of AI-driven credit and advice decisions; core migration slippage delaying the data foundation; and colleague adoption — the difference between a deployed copilot and a used one.

Upside risk is distributional. In a ~2% growth market, a bank that compresses cost-to-income by 14 points takes share from peers who cannot, and does so with better credit outcomes rather than looser underwriting.

06

The AI transformation roadmap: five phases to leadership

Phase 1 (0–6 months) is foundation: data foundation and governance, AI use case prioritisation, building pilot capabilities, quick wins in delivery, and a change and communications kick-off.

Phase 2 (6–18 months) is optimisation: process automation at scale, AI copilots for employees, fraud and risk models, customer experience roll-out and cloud migration acceleration. Phase 3 (18–36 months) is scale and growth: AI-driven personalisation, advanced credit and risk models, open banking and ecosystem plays, and data monetisation initiatives.

Phase 4 (36–60 months) is ecosystem expansion: platform business models, partner and fintech integration, AI marketplace and APIs, sustainability solutions and international opportunities. Phase 5 (60+ months) is AI-led leadership: autonomous banking operations, AI-driven strategic planning, industry benchmark and thought leadership, continuous innovation and long-term value compounding.
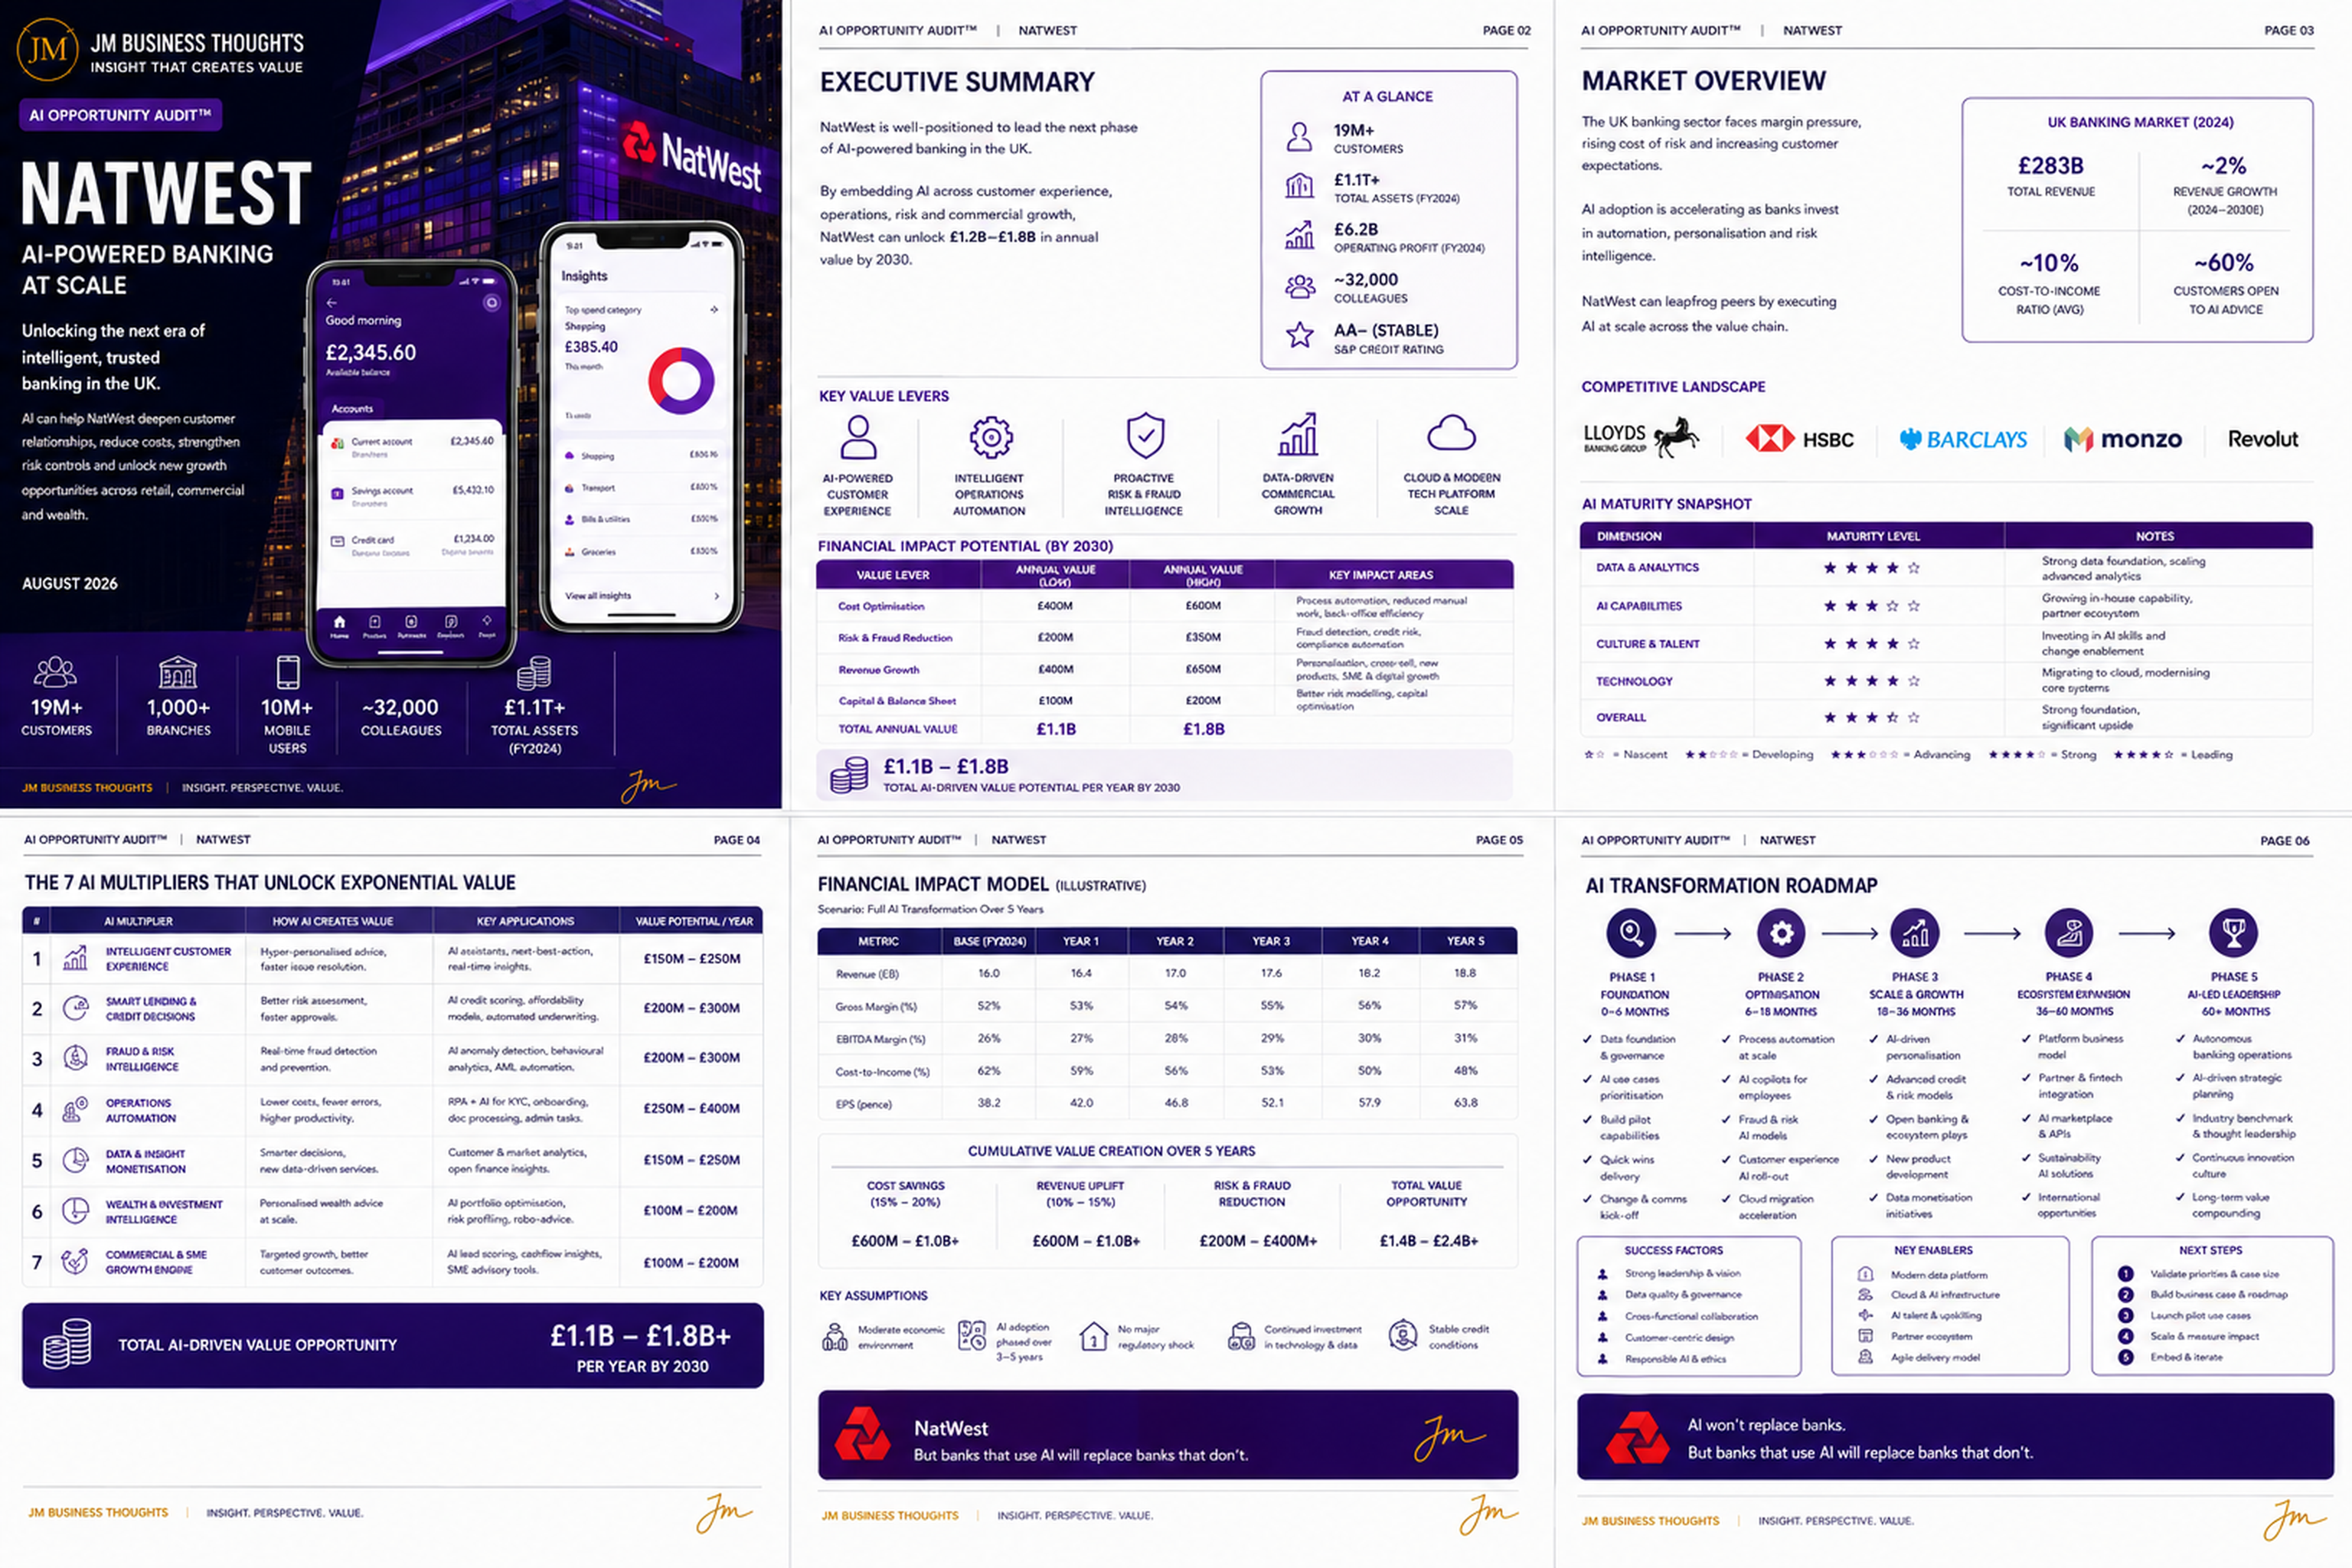
  • Success factors: strong leadership and vision, data quality and governance, cross-functional collaboration, customer-centric design, responsible AI and ethics
  • Key enablers: modern data platform, cloud and AI infrastructure, AI talent and upskilling, partner ecosystem, agile delivery model
  • Next steps: validate priorities and case size, build business case and roadmap, launch pilot use cases, scale and measure impact, embed and iterate

The Multiplier Framework

7 compounding levers

Seven AI multipliers unlock exponential value across NatWest's retail, commercial and wealth franchises — sized to £1.1BN – £1.8BN+ per year by 2030.

01

Intelligent Customer Experience

£150M – £250M / year

  • AI assistants and next-best-action across app and contact centre
  • Hyper-personalised advice and faster issue resolution
  • Real-time insights surfaced at the moment of decision

Outcome · Service cost falls while relationship depth rises

02

Smart Lending & Credit Decisions

£200M – £300M / year

  • AI credit scoring and affordability models
  • Automated underwriting with human oversight
  • Better risk assessment, faster approvals

Outcome · More lending at better credit quality, not looser underwriting

03

Fraud & Risk Intelligence

£200M – £300M / year

  • Anomaly detection across behavioural, transaction and AML signals
  • Real-time fraud detection and prevention
  • Compliance monitoring at portfolio scale

Outcome · Losses avoided before they crystallise on the P&L

04

Operations Automation

£250M – £400M / year

  • RPA plus AI for KYC, onboarding and document processing
  • Admin task automation across back office
  • Lower cost, fewer errors, higher productivity

Outcome · The largest single contributor to cost-to-income compression

05

Data & Insight Monetisation

£150M – £200M / year

  • Customer and market analytics as a product
  • Open banking insights for commercial clients
  • Smarter decisions from new data-driven services

Outcome · A revenue line that does not consume balance sheet

06

Wealth & Investment Intelligence

£100M – £200M / year

  • AI portfolio optimisation and risk profiling
  • Robo-advice and personalised wealth advice at scale
  • Advice economics that work below the private-bank threshold

Outcome · Targeted growth in the highest-margin franchise

07

Commercial & SME Growth Engine

£100M – £200M / year

  • AI lead scoring and cashflow insights for SME clients
  • SME advisory tools embedded in the banking relationship
  • Targeted growth and better customer outcomes

Outcome · NatWest's SME franchise defended against fintech encroachment

NatWest: AI-Powered Banking At Scale. full strategic breakdown
AI Opportunity Audit™: NatWest — the full six-page report covering executive summary and key value levers, UK market overview and competitive landscape, the AI maturity snapshot, the seven AI multipliers, the illustrative five-year financial impact model and the five-phase AI transformation roadmap.

The Verdict

AI won't replace banks. But banks that use AI will replace banks that don't. For NatWest, that is £1.1BN – £1.8BN of annual value by 2030, a 14-point compression in cost-to-income and the option to lead UK banking rather than track it.

JM founder signature
68 · PureGym — Fitness At Scale. More Personal. More Inclusive.67 · SIXT — Smarter Mobility. Greater Availability. A More Connected Tomorrow.66 · Sendwave — Money That Moves With Intelligence.65 · McDonald’s — Serving The Future With AI.64 · Compare the Market — Smarter Comparison. Better Matches. Brighter Tomorrows.63 · WeBuyAnyCar — Smarter Pricing. Faster Offers. Better Conversion.62 · Primark — Affordable Fashion. Greater Possibilities With AI.61 · Starbucks — Smarter Stores. Stronger Loyalty. Better Margins.60 · IKEA — AI-Powered Home Retail at Global Scale59 · H&M — Smarter Fashion. Brighter Tomorrow.58 · WeWork — The Value Wasn't Lost. It Was Mispriced.57 · Yahoo — The Value Wasn't Lost. It Was Mispriced.56 · Nando's UK — Smarter Restaurants. Stronger Loyalty. Better Margins.55 · The Amplifier54 · The Body Shop53 · Arcadia Group52 · Cazoo51 · Blockbuster50 · Carpetright49 · Wilko48 · Mothercare47 · Phones 4u46 · Farfetch45 · Jumia44 · Toys ‘R’ Us43 · The Collateral Gap — Part One41 · The Amplifier40 · Africa Bee Farming39 · Kenya Airways38 · Africa Greenhouse Farming37 · Uganda Tourism Board36 · Boots UK35 · Biffa (UK)33 · The Audit32 · The Lean Company31 · Africa Mushroom Farming29 · The Rider Economy Nobody Verified28 · The Layer Underneath the Layer27 · Independent Timber Yards & Jewson Timber26 · Link Up TV & GRM Daily25 · East African Portland Cement42 · International Student Credential & Financial Verification — Part One24 · The Supply Chain Inside the Supply Chain23 · The White Space, Mapped22 · The Real Opportunity21 · Greencore20 · West Ham United19 · Roofings Group Uganda18 · Mombasa Port17 · Auto Trader UK16 · Uganda Coffee Development Authority15 · Brookside Dairy14 · GraceKennedy13 · Rightmove12 · Manchester United11 · Greggs30 · Twiga Foods10 · Uchumi09 · Konga08 · Edcon09 · GAME07 · Debenhams06 · Claire's05 · Boohoo04 · Argos