Mothercare: The Value Wasn’t Lost. It Was Mispriced. research poster
All Research
48Mispriced Assets™ 20 min readAugust 2026
Coverage · United Kingdom · 31 Countries · Institutional CoverageSector · Parenting Retail · Franchise, Brand & Digital CommerceFormat · Six-page audit

MothercareA Case Study In Strategic Value Overlooked, Not Destroyed.

Mothercare carries 60+ years of parenting trust, operates across 31 countries through 370+ stores and 48 e-commerce platforms, and delivered £230.6M of FY25 franchise retail sales. The UK store estate closed; the brand did not. What failed was owned retail economics, not the parenting proposition. This audit sizes £15M – £30M+ of annual AI-driven value by 2030 by turning fragmented franchise, store and digital data into one intelligent customer and commercial system.

Years Of Parenting Trust

60+

Countries

31

Stores

370+

E-Commerce Platforms

48

FY25 Franchise Retail Sales

£230.6M

Online Share Of Sales

9%

Physical Retail Share

90%

Annual AI Value By 2030

£15M – £30M+

The Thesis

Mothercare is a globally recognised parenting brand operating through an established franchise network. Its advantage is trust across the full parenting lifecycle — pregnancy, newborn, toddler, pre-school — the single most predictable, highest-intent consumer journey in retail. Its challenge is that this advantage is spread across 31 countries, 370+ stores, 48 separate e-commerce platforms and a set of franchise partners who each hold a fragment of the data. Nobody owns the customer record. The market priced the closure of the UK owned estate as the end of the business; what actually remains is a £230.6M franchise revenue base attached to sixty years of trust and almost no intelligence layer. Unify the partner data, personalise the lifecycle, optimise inventory and raise franchise visibility, and the same network generates £15M – £30M+ of annual value by 2030 with no new market entry.

Exhibit · Report Cover

48 · Mispriced Assets™

Mothercare: The Value Wasn’t Lost. It Was Mispriced. report cover
Mothercare: The Value Wasn’t Lost. It Was Mispriced.August 2026 · United Kingdom · 31 Countries · Institutional Coverage
01

Executive summary: trust at scale, data in fragments

Mothercare is a globally recognised parenting brand operating an established franchise network. Its advantage is trust across the full parenting lifecycle; its challenge is turning fragmented partner, store and digital data into one intelligent customer and commercial system.

AI can strengthen lifecycle personalisation, inventory decisions, franchise visibility, product discovery and service quality — creating an illustrative £15M – £30M+ of annual value potential by 2030.

The at-a-glance position: founded 1961, 60+ years of parenting trust, 31 countries, 370+ stores, 48 e-commerce platforms, £230.6M FY25 retail sales and a 9% online share.

The key value levers resolve into seven lines: lifecycle personalisation (£4M – £7M), demand and inventory optimisation (£3M – £6M), franchise performance intelligence (£2M – £4M), product discovery and conversion (£2M – £4M), customer service automation (£1M – £2M), product safety and compliance (£1M – £2M) and data and decision intelligence (£2M – £5M).

£15M – £30M+ of illustrative annual AI-driven value by 2030 — on a £230.6M franchise sales base.
  • Founded 1961 — 60+ years of parenting trust
  • 31 countries, 370+ stores, 48 e-commerce platforms
  • £230.6M FY25 franchise retail sales; 9% online share; 90% physical retail
  • Seven value levers aggregating to £15M – £30M+ per year by 2030
02

The mispricing: what closed versus what remains

Mothercare’s UK retail administration is remembered as the end of the brand. It was the end of one channel in one country — owned big-box parenting retail carrying full property and inventory risk.

What remains is structurally different and materially undervalued. A franchise network across 31 countries generating £230.6M of retail sales, in which Mothercare carries brand and product economics without the property risk that caused the failure. That is a licensing and wholesale business inside a retail valuation.

The brand itself is the largest mispriced line. Sixty-plus years of parenting trust is not marketing equity; it is safety equity. Parents transfer it generationally, and it decides purchase in the one category where price sensitivity is lowest and error tolerance is zero.

The lifecycle data is the second. Pregnancy through pre-school is a five-year, dated, predictable purchase sequence — the single most valuable customer timeline in consumer retail. Across 48 platforms and 370+ franchise stores it exists but is unreadable, because no unified product taxonomy or shared data model connects it.

The third is franchise leverage. Partner performance varies widely by market, with no shared dashboarding, benchmarking or anomaly detection. Consistent partner execution is worth £2M – £4M a year on its own — and it requires visibility, not capital.

A licensing and wholesale business with 60 years of safety equity, priced as a closed UK retailer.
  • What failed: owned UK big-box retail economics with property and inventory risk
  • What remains: £230.6M franchise sales across 31 countries, brand-led, capital-light
  • Brand: 60+ years of transferable, generational parenting trust
  • Data: a five-year dated lifecycle spread across 48 platforms and 370+ stores
  • Franchise: wide partner variance with no shared performance intelligence
03

Market and digital overview: omnichannel parenting

Parenting retail is moving toward trusted omnichannel journeys, lifecycle-led personalisation and faster local fulfilment. Mothercare’s franchise scale creates a strong platform — but data and execution vary across markets.

The digital position quantifies the gap: 31 countries, 370+ stores, 48 digital platforms, 9% online sales and 90% physical retail. A 9% online share in a category that is now researched online in nearly every market is not a demand ceiling; it is an execution gap.

Five market dynamics define the opportunity: lifecycle loyalty, trust and safety, omnichannel discovery, local market relevance and franchise scale. Each is an AI problem before it is a merchandising one — lifecycle loyalty is a prediction task, trust and safety is a compliance-monitoring task, discovery is a semantic search task, local relevance is a localisation task and franchise scale is a benchmarking task.

The AI maturity snapshot reads consistently across dimensions. Data and analytics: developing data foundation. AI capabilities: early initiatives. Technology and platforms: modernising platforms. Customer experience: improving consistency. Franchise operations: increasing visibility. Inventory and supply: building capabilities. Overall: strong foundation, high upside.

9% online in a category researched online everywhere. That is an execution gap, not a demand ceiling.
  • 31 countries · 370+ stores · 48 digital platforms
  • 9% online sales vs 90% physical retail
  • Dynamics: lifecycle loyalty, trust and safety, omnichannel discovery, local relevance, franchise scale
  • AI maturity overall: strong foundation, high upside
04

Where the value actually leaks

Four leaks dominate a franchise-led parenting network, and none appear in a headline royalty line.

The first is lifecycle timing. Every parent moves through age and stage windows on a known schedule. Missing the window costs the entire basket to a competitor who did not — and a stage-based journey engine recovers £4M – £7M a year of relevance and retention.

The second is stockouts and markdowns. Parenting demand is seasonal, stage-driven and highly local; franchise partners forecast independently with limited signal. Fewer stockouts and markdowns is worth £3M – £6M a year.

The third is discovery. Buggies, car seats and nursery are the definition of a high-consideration, safety-led, specification-heavy purchase. Semantic search, guided bundles and recommendation make product choice easier and safer — £2M – £4M a year.

The fourth is trust integrity. Product safety, recall monitoring, review intelligence and compliance across 31 regulatory regimes is where a parenting brand is genuinely fragile. Compliance monitoring and risk alerts are worth £2M – £4M a year and protect the sixty-year asset the whole business rests on.

  • Lifecycle timing gap: missed age and stage windows lose the whole basket
  • Inventory gap: independent franchise forecasting driving stockouts and markdown
  • Discovery gap: safety-led, specification-heavy choice with generic search
  • Integrity gap: safety, recall and compliance monitoring across 31 regimes
05

Financial impact model: base FY25 to Year 5

The illustrative model runs a disciplined AI transformation across five years from a base FY25.

Franchise retail sales (£M) move 230.6 → 238 → 248 → 260 → 275 → 292. Online share moves 9% → 10% → 12% → 14% → 17% → 20% — the mix shift, not the headline growth, is where the margin sits.

AI investment (£M) runs — → 3 → 5 → 6 → 6 → 5 against AI-driven value (£M) of — → 3 → 7 → 12 → 19 → 27, giving cumulative AI value (£M) of — → 3 → 10 → 22 → 41 → 68. The programme pays back inside year two and compounds thereafter.

By 2030 the annual value resolves into four blocks: revenue and retention £7M – £12M, inventory and margin £4M – £8M, franchise and operations £2M – £5M, and service and risk £2M – £5M — a total annual value by 2030 of £15M – £30M+.

Key assumptions: partner participation, a shared data model, phased investment, strong governance and market-by-market adoption. None of them require capital intensity; all of them require franchise alignment.

Online share 9% → 20%. Cumulative AI value £68M over five years on £25M of investment.
  • Franchise retail sales (£M): 230.6 → 238 → 248 → 260 → 275 → 292
  • Online share: 9% → 10% → 12% → 14% → 17% → 20%
  • AI investment (£M): — → 3 → 5 → 6 → 6 → 5
  • AI-driven value (£M): — → 3 → 7 → 12 → 19 → 27
  • Cumulative AI value (£M): — → 3 → 10 → 22 → 41 → 68
  • By 2030: revenue and retention £7M–£12M; inventory and margin £4M–£8M; franchise and ops £2M–£5M; service and risk £2M–£5M
06

AI transformation roadmap: five phases

Phase 1 (0–6 months) — Foundation: data audit and governance, partner baseline, priority use cases, KPIs and safety principles.

Phase 2 (6–12 months) — Pilots and capability: lifecycle CRM pilot, demand forecasting, search and recommendations, multilingual service assistant.

Phase 3 (12–24 months) — Scale across franchise: shared partner dashboards, inventory optimisation, localised AI models, unified product intelligence.

Phase 4 (24–36 months) — Omnichannel integration: connected customer journeys, intelligent fulfilment, next-best-action, automated reporting.

Phase 5 (36+ months) — Lead and innovate: a parenting intelligence platform, predictive lifecycle engagement, partner ecosystem services, continuous AI optimisation.

Success factors: brand trust and safety, franchise alignment, customer consent, measurable ROI and local market relevance. Key enablers: a modern data platform, unified product taxonomy, responsible AI governance, skilled teams and strategic partners. Next steps: validate baselines, secure partner participation, prioritise three pilots, launch a twelve-month programme, and measure, learn and scale.
Trusted for generations. Intelligent for every stage.

The Multiplier Framework

7 compounding levers

Seven AI multipliers, each with a defined mechanism, application set and annual value range — aggregating to £15M – £30M+ of illustrative AI-driven value per year by 2030 across the existing franchise network.

01

Lifecycle Personalisation

Stage-based journeys, relevance and retention across the full parenting timeline.

  • Next-best product, age and stage CRM
  • Personalised content across pregnancy to pre-school
  • Dated trigger campaigns on the known lifecycle schedule

Outcome · £4M – £7M per year

02

Demand & Inventory Optimisation

Fewer stockouts and markdowns across 370+ stores and 31 markets.

  • Forecasting by market, season and stage
  • Allocation and replenishment across franchise partners
  • Markdown and terminal-stock control

Outcome · £3M – £6M per year

03

Franchise Performance Intelligence

Consistent partner execution across a 31-country network.

  • Market dashboards and shared benchmarks
  • Anomaly detection on sales, stock and service
  • Partner coaching driven by comparative data

Outcome · £2M – £4M per year

04

Product Discovery & Conversion

Easier, safer product choice in a specification-heavy category.

  • Recommendations and semantic search
  • Guided bundles for nursery, travel and feeding
  • Localised assortment surfacing across 48 platforms

Outcome · £2M – £4M per year

05

Conversational Parenting Assistant

Trusted 24/7 guidance in the moments parents actually decide.

  • Multilingual chat and product Q&A
  • Care journeys and stage guidance
  • Escalation into store and partner expertise

Outcome · £1M – £3M per year

06

Customer Service Automation

Faster resolution at lower cost across markets and languages.

  • Agent assist and automated case resolution
  • Returns and delivery support
  • Self-serve tooling across the franchise base

Outcome · £1M – £2M per year

07

Product Safety & Data Intelligence

Stronger trust and faster decisions — protecting the sixty-year asset.

  • Compliance monitoring across 31 regulatory regimes
  • Review intelligence and early risk alerts
  • Unified data and executive decision reporting

Outcome · £2M – £4M per year

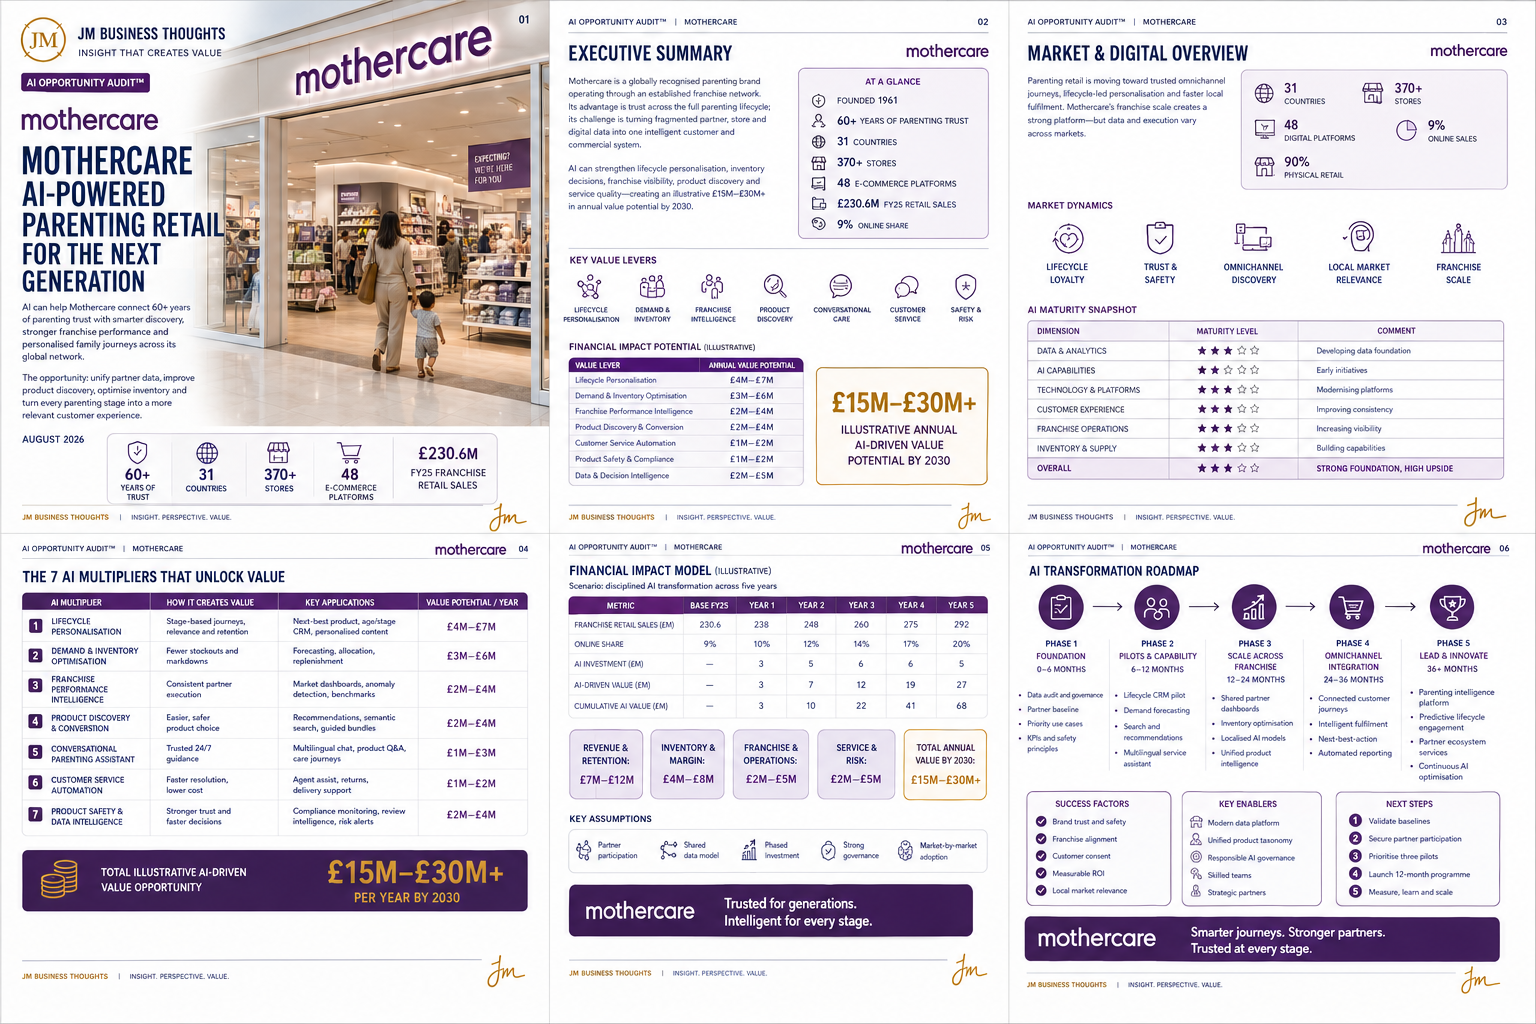
Mothercare: The Value Wasn’t Lost. It Was Mispriced. full strategic breakdown
Mispriced Assets™ · UK & Global Retail Lost Giants — Mothercare: the full six-page institutional report covering the cover and at-a-glance estate, executive summary and key value levers, market and digital overview with the AI maturity snapshot, the seven AI multipliers, the five-year financial impact model and key assumptions, and the five-phase AI transformation roadmap.

The Verdict

Sixty-plus years of parenting trust, 31 countries, 370+ stores, 48 platforms and £230.6M of franchise retail sales — written down with a UK store estate that was only ever one channel in one market. The category did not move away; the data simply never got joined. Seven multipliers turn fragmented partner, store and digital data into one intelligent customer system worth £15M – £30M+ a year by 2030, with online share moving 9% to 20% and £68M of cumulative value on £25M of investment. Smarter journeys. Stronger partners. Trusted at every stage.

JM founder signature
68 · PureGym — Fitness At Scale. More Personal. More Inclusive.67 · SIXT — Smarter Mobility. Greater Availability. A More Connected Tomorrow.66 · Sendwave — Money That Moves With Intelligence.65 · McDonald’s — Serving The Future With AI.64 · Compare the Market — Smarter Comparison. Better Matches. Brighter Tomorrows.63 · WeBuyAnyCar — Smarter Pricing. Faster Offers. Better Conversion.62 · Primark — Affordable Fashion. Greater Possibilities With AI.61 · Starbucks — Smarter Stores. Stronger Loyalty. Better Margins.60 · IKEA — AI-Powered Home Retail at Global Scale59 · H&M — Smarter Fashion. Brighter Tomorrow.58 · WeWork — The Value Wasn't Lost. It Was Mispriced.57 · Yahoo — The Value Wasn't Lost. It Was Mispriced.56 · Nando's UK — Smarter Restaurants. Stronger Loyalty. Better Margins.55 · The Amplifier54 · The Body Shop53 · Arcadia Group52 · Cazoo51 · Blockbuster50 · Carpetright49 · Wilko46 · Farfetch45 · Jumia44 · Toys ‘R’ Us43 · The Collateral Gap — Part One41 · The Amplifier40 · Africa Bee Farming39 · Kenya Airways38 · Africa Greenhouse Farming37 · Uganda Tourism Board36 · Boots UK35 · Biffa (UK)34 · NatWest33 · Skip Hire Companies UK33 · The Audit32 · The Lean Company31 · Africa Mushroom Farming29 · The Rider Economy Nobody Verified28 · The Layer Underneath the Layer27 · Independent Timber Yards & Jewson Timber26 · Link Up TV & GRM Daily25 · East African Portland Cement42 · International Student Credential & Financial Verification — Part One24 · The Supply Chain Inside the Supply Chain23 · The White Space, Mapped22 · The Real Opportunity21 · Greencore20 · West Ham United19 · Roofings Group Uganda18 · Mombasa Port17 · Auto Trader UK16 · Uganda Coffee Development Authority15 · Brookside Dairy14 · GraceKennedy13 · Rightmove12 · Manchester United11 · Greggs30 · Twiga Foods10 · Uchumi09 · Konga08 · Edcon09 · GAME07 · Debenhams06 · Claire's05 · Boohoo04 · Argos